(905) 441 0770 allen@allenehlert.com

Millennials Brace for Economic Pain

by | May 2, 2025

As the economy cools and interest rates rise, a new report from RBC warns that millennials and young Gen X homeowners could face significant financial challenges. High debt and vulnerability to a potential economic downturn are raising concerns about the ability of young workers to maintain employment and make mortgage payments. With the potential for mortgage payments to increase by 25% next year, the housing market is also a cause for concern. In this blog post, we dive deeper into the findings of the RBC report and explore the implications for millennials.
Millennials Brace for Economic Pain

The Rising Debt Burden

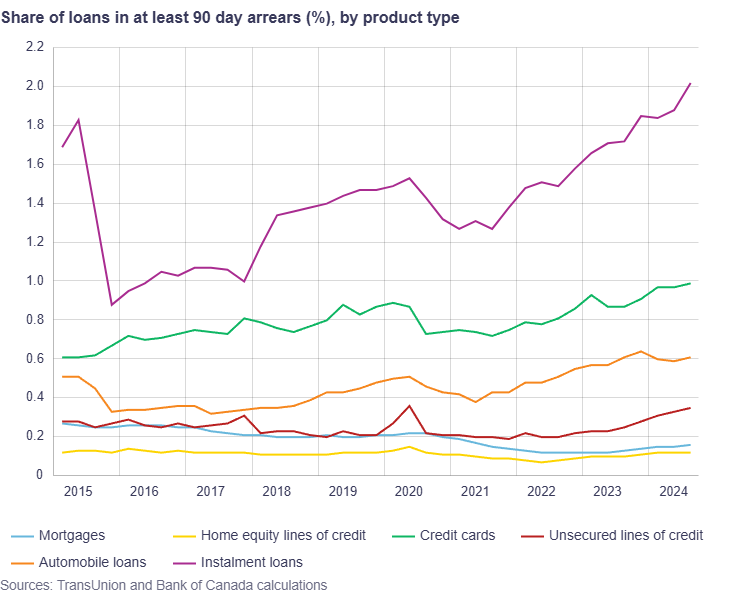
Millennials in Canada are carrying the largest debt load, making them particularly vulnerable to any shifts in the economy. With high levels of student loan debt combined with rising home prices, millennials are finding it increasingly difficult to manage their finances. The report from RBC highlights the potential consequences of this debt burden, including the risk of foreclosure if full-time employment is lost.
Impact of Variable Interest Rates

Variable interest rates have hit millennials hard, but many have managed to keep up with their mortgage payments or refinance at lower rates. However, if the economy cools down and millennials lose full-time employment, banks may be forced to foreclose on houses. This could have a substantial impact on the housing market, with the potential for prices to decline and sales to slow down.

The Housing Market Concerns

The RBC report also raises concerns about the current state of the housing market and the potential for a collapse or correction. Despite record immigration numbers, the housing market remains supply-constrained, leading to high prices and affordability issues. Uncertainty surrounds when a major correction will occur and how it will impact millennials who are heavily invested in the market.

The RBC report paints a challenging picture for millennials in the months ahead. The combination of high debt, potential job losses, and a volatile housing market creates significant economic pain for this generation.

Mortgage and Money Radio Logo
Allen Ehlert

Allen Ehlert

Allen Ehlert is a licensed mortgage agent. He has four university degrees, including two Masters degrees, and specializes in real estate finance, development, and investing. Allen Ehlert has decades of independent consulting experience for companies and governments, including the Ontario Real Estate Association, Deloitte, City of Toronto, Enbridge, and the Ministry of Finance.

BMO, TD, Scotiabank ReAdvanceable Mortgages: How to Choose?

Mortgages are in some ways a lot like pharmaceuticals. A drug that is good for one person is bad for another. So too is it with mortgages and financial products in general. This is why it is important to work with a licensed professional to discover the mortgage that...
Private Mortgage Helps During Divorce

Private Mortgages Support Divorce

Discover how getting a private mortgage can be a solution during divorce and can solve a multitude of challenges

Economic Pulse

The Economic Pulse of Canadian Households

Every quarter, Statistics Canada provides us with a deeper look into the financial realities of Canadian households. The most recent release from the Distributions of Household Economic Accounts sheds light on how Canadians are managing their income, savings, debt,...
Financing Renos and Remodels

Financing Renos and Remodels

Renovating a home can be a smart investment, but strategic financing is crucial to maximizing returns while avoiding unnecessary financial strain. Choosing the right funding option can determine how much you can invest in upgrades, and understanding how appraisers...
Closing Date Roulette

Closing Date Roulette

Closing Date Roulette: You have negotiated the price, crossed your fingers through the home inspection and finally agreed on a closing date. Everyone takes a breath. Deal done, right? Not quite. The date written into your Agreement of Purchase and Sale can quietly determine whether you pay a mortgage penalty, need bridge financing, qualify for a port, require a short open mortgage, or miss the cleanest opportunity to change lenders.

Private Mortgage: Debt Consolidation

Private Mortgage Enables Debt Consolidation

Jessica, a homeowner in Brampton, Ontario, has accumulated $85,000 in high-interest debt, including: $40,000 in credit card balances (interest rates of 19-24%) $25,000 in personal loans (interest rate of 12%) $20,000 in a car loan (interest rate of 9%) She owns a...
Understanding Bankruptcy

Understanding Bankruptcy in Canada

Bankruptcy is a legal proceeding under the Bankruptcy and Insolvency Act (BIA) intended to relieve individuals or businesses who cannot pay their debts by legally discharging eligible debts. It provides protection against creditors, allowing you to rebuild your...
Readvancable Mortgage

Readvanceable Mortgages: The Collateral Difference

Collateral mortgages—such as the TD Home Equity FlexLine, BMO Homeowner ReadiLine, and Scotiabank STEP mortgage—differ significantly from conventional mortgages in several important ways. Understanding these differences can help homeowners decide which type best...
Negative Interest RatesL Dangerous Experiment

What are Negative Interest Rates

Decoding Negative Interest Rates: A Game Changer in Economics Negative interest rates have the potential to revolutionize the financial landscape, with central banks using this unconventional tool to spur economic activity. The concept of charging lenders for holding...

Understanding Refinancing

Understanding Refinancing: Refinancing is how you put your home equity to work, whether that means wiping out high-interest debt, funding a renovation, helping the kids, or finally breathing a little easier at the end of the month. But refinancing comes with its own vocabulary, rules and price tag.