(905) 441 0770 allen@allenehlert.com

The Inverted Yield Curve Omen

by | July 24, 2025

Demystifying the Inverted Yield Curve Phenomenon

Have you ever wondered why investors are so obsessed with the inverted yield curve? Let’s dive into the world of finance and understand why this concept holds such significance in predicting economic trends.

What is the Yield Curve?

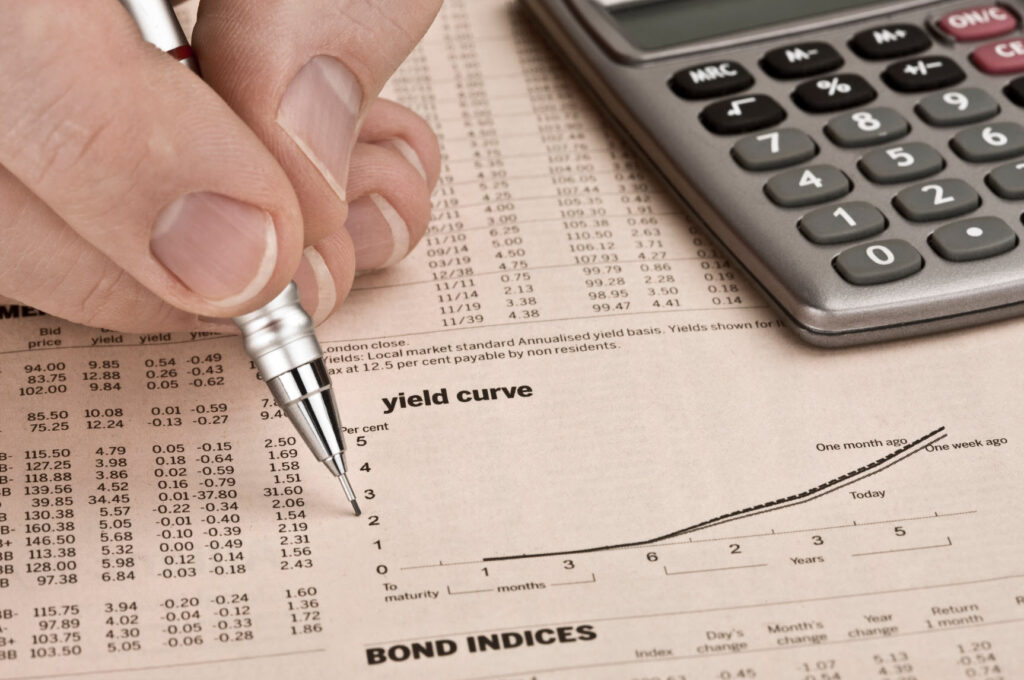
The yield curve reflects the difference between short-term and long-term bond yields. It provides insights into the bond market and the expected return on investment over time. By understanding the yield curve, investors gain valuable clues about the state of the economy and potential market trends. With a healthy yield curve, bonds that mature soon provide a lower interest rate than bonds that mature later to reflect the greater risk due to more bad things that could happen given more time reflected in the longer dated bond.

Key Factors Influencing the Yield Curve

The yield curve is influenced by various factors, including the Bank of Canada’s monetary policies, the Government of Canada’s fiscal policies, market demand for bonds, and overall economic conditions. For instance, the Bank of Canada’s actions to control inflation by raising interest rates to slow down borrowing can impact short-term bond yields, ultimately affecting the shape of the yield curve.
Obsessed with the Yield Curve

When investors think the economy is doing well, they take money out of longer term bonds and put their money to work in riskier type assets, like stocks. As they sell their bonds, bond prices fall as demand for bonds decrease which in turn, increases the bonds yield, as the price of a bond and the interest it pays is inversely related to each other. Alternatively, when investors get nervous about the economy, they start to sell their risk on assets, and buy more conservative investments, like bonds, and real estate, causing rates to drop and bond prices (and real estate prices) to rise.

Interpreting the Inverted Yield Curve

What causes the yield curve to change shape and invert, meaning, when the yield curve inverts, short-term bond yields go higher than long-term yields, it often serves as a warning sign for an impending recession. However, it’s crucial to note that the inverted yield curve is not foolproof and requires careful analysis in conjunction with other economic indicators. Yet historically, it is rare for a yield curve to invert and a recession not to follow.

Real-World Implications and Economic Forecasts

Investors and economists closely monitor the yield curve to gauge the economy’s health and make informed investment decisions. The dynamics of the yield curve, especially during periods of flattening or inversion, prompt strategic adjustments in asset allocation and risk management strategies.

Conclusion:

In conclusion, understanding the intricacies of the yield curve, particularly the implications of an inverted yield curve, equips investors with valuable insights for potential market downturns. It serves as a critical tool for assessing economic conditions and making informed investment decisions.

Mortgage and Money Radio Logo
Allen Ehlert

Allen Ehlert

Allen Ehlert is a licensed mortgage agent. He has four university degrees, including two Masters degrees, and specializes in real estate finance, development, and investing. Allen Ehlert has decades of independent consulting experience for companies and governments, including the Ontario Real Estate Association, Deloitte, City of Toronto, Enbridge, and the Ministry of Finance.

What is a Second Mortgage?

What is a Second Mortgage?

A second mortgage is a loan that is secured against a property that already has an existing mortgage. It is considered "second" because it is subordinate to the first mortgage in terms of priority—meaning that if the homeowner defaults, the first mortgage lender gets...
Housing Supply

10 Factors Impacting Housing Supply

A complex interplay of various factors affects the supply of housing in Ontario. These factors can affect the availability, type, and affordability of housing in the province. Here are ten key factors impacting the supply of housing in Ontario: 1. Land Availability...
Getting a Second Mortgage

Getting a Second Mortgage

If you have a first mortgage, can you just go out and get a second mortgage? The short answer is not always. While it is possible to obtain a second mortgage if you already have a first mortgage, several factors must align for you to qualify. You cannot simply go and...
Non Conforming Apartment

Non-Conforming Apartment Income

As a mortgage agent who underwrites mortgages, I’ve come across countless applications where homeowners and investors alike want to leverage rental income from basement suites or converted spaces to boost their borrowing power. It's a smart move in theory, but the...
Affordable Housing

Ontario’s 10 Most Affordable Cities

Affordability remains a cornerstone of housing decisions, often outweighing even employment factors when individuals and families consider relocating. In Ontario, a diverse province with a wide range of urban and rural settings, certain cities stand out for their...
Toronto Traffic

10 Shortest Ontario Commute Cities

A short commute to work really improves the quality of your life. Workers don't push for remote work if they can live in a community where the commute is short and pleasant. However, if your employer is in a major city, or worse yet, Toronto, and the demand is for you...
Understanding Subordination Agreement

Understanding Subordination Agreements

A subordination agreement is a legal document that modifies the lien priority of two or more mortgages on a property. In the context of first and second position mortgages, this agreement allows a lender with a lower-ranking mortgage (such as a second mortgage or a...
Break Your Mortgage

How to Break A Mortgage

Breaking a mortgage in Ontario, Canada, before the end of its term can lead to significant penalties. It's important to understand these penalties and how they are calculated. Here are the key points to consider: Types of Penalties Interest Rate Differential (IRD)...
Lock In Your Rate

How to Lock in a Good Rate

Locking in a good mortgage rate is a key step in the home-buying process, especially in a fluctuating interest rate environment. Here are steps and strategies to help you secure a favourable rate: Understand Rate Locks Monitor Interest Rates Improve Your Credit Score...
Variable Mortgage Strategy

10 Variable Mortgage Strategies

When opting for a variable-rate mortgage, it's important to have strategies in place to manage the potential fluctuations in interest rates and to maximize the benefits of this type of mortgage. In this article, let me give you 10 effective strategies to help you...








