
… Stretching every dollar to make your mortgage affordable for you
Living in Canada has gotten downright expensive. Between the taxes that cost more than everything else put together, grocery bills that balloon every week, and the cost of housing that feels like it’s been strapped to a rocket, Canadians are stuck in what feels like a never-ending affordability crunch. Many families are lying awake at night, staring at the ceiling, wondering how they’ll keep that all-important roof over their heads.
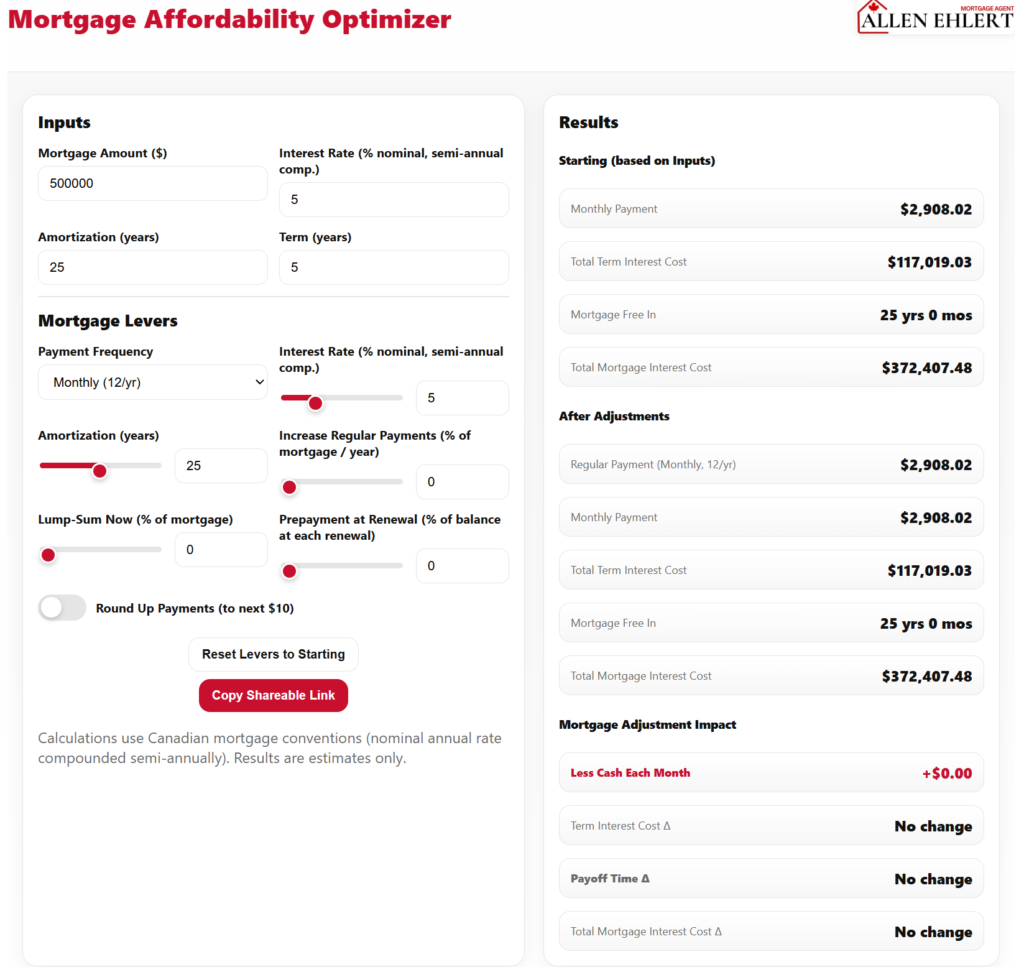
Enter Allen Ehlert’s Ultimate Canadian Mortgage Affordability Optimizer—a one-of-a-kind calculator designed to give you control. It’s not just another mortgage payment estimator. It’s a full-blown optimization tool that lets you tweak, test, and adjust every lever of your mortgage until you find the sweet spot that works for your budget. Think of it as your personal financial tuning fork—helping you hit the perfect note in a world of rising costs.
Here’s what we’ll cover today:
Understanding the Affordability Crunch
How the Mortgage Affordability Optimizer Works
Playing With the Variables (and Why It Matters)
Real-World Examples for Realtors and Clients
A Story That Brings It All Home
Understanding the Affordability Crunch
The affordability crisis isn’t just a headline—it’s a lived reality. Taxes are higher than ever, wages haven’t kept up with inflation, and food costs make you wonder if gold is cheaper than lettuce. Add in rising interest rates, and suddenly, that dream home feels a little out of reach.
This is why planning matters more than ever. The old way of just plugging numbers into a basic mortgage calculator doesn’t cut it anymore. You need something that allows you to model different strategies, test out what-ifs, and actually optimize affordability. That’s exactly what Allen’s Optimizer does.
How the Mortgage Affordability Optimizer Works
The Optimizer is designed to put you in the driver’s seat. Here’s how you use it:
- Enter your target home price.
- Select your down payment amount.
- Play with mortgage term and amortization period.
- Adjust the interest rate to see how future hikes or drops impact you.
- Layer in property taxes, condo fees, and insurance.
- Review the monthly payment output—and adjust until it fits your budget.
Instead of a static “take-it-or-leave-it” number, you get a full range of scenarios. You can ask: What if I stretched to 30 years instead of 25? What if I wait until rates drop a half point? What if I go fixed instead of variable? The Optimizer shows you instantly how those decisions affect your affordability.
Playing With the Variables (and Why It Matters)
Mortgage affordability isn’t one-size-fits-all—it’s a balancing act. The Optimizer lets you manipulate every factor that impacts your monthly payment.
- Amortization length: Longer terms mean lower monthly payments (though more interest overall).
- Interest rates: Locking in at the right time can mean the difference between “comfortable” and “crushing.”
- Down payment: Increasing it—even by a little—can lower your costs more than you’d think.
- Additional costs: Property taxes, condo fees, and insurance often get forgotten, but they’re real monthly obligations.
By seeing how these elements interact in real-time, you can make better choices—not just about buying a home, but about protecting your lifestyle.
Real-World Examples for Realtors and Clients
For clients, the Optimizer is like a financial rehearsal. You get to test drive different scenarios before committing. Maybe you find that with a slightly bigger down payment, you can move into a neighbourhood you thought was out of reach. Or maybe you realize you’re better off waiting six months until interest rates ease.
For realtors, this is a golden resource. You can sit down with buyers and show them exactly what their monthly obligations would look like across different properties. No more deer-in-the-headlights moments when buyers discover hidden costs late in the game. Instead, you’re building trust and setting expectations clearly.
A Story That Brings It All Home
Take Alex and Maya. They were looking at a $750,000 townhouse in Peterborough. They had $60,000 for a down payment and were ready to go. But when they ran the numbers through the Optimizer, reality hit—monthly payments plus property taxes were going to stretch them to the breaking point.
Instead of panicking, they started tweaking. What if they stretched amortization to 30 years? What if they increased their down payment by waiting three months and saving another $10,000? What if they considered a slightly less expensive home in a nearby neighbourhood?
Within minutes, they found a scenario that gave them breathing room—a home they loved and a payment they could live with. The Optimizer didn’t just show them numbers; it showed them peace of mind.
Allen’s Final Thoughts
In today’s Canada, every dollar counts. Housing isn’t getting cheaper, and pretending it will only leads to heartbreak. The key isn’t waiting for the market to change—it’s learning how to navigate it smartly.
That’s why I built the Ultimate Mortgage Affordability Optimizer. It empowers you to take control of your financial future by showing you exactly how your decisions impact your monthly reality. No fluff, no guesswork—just clarity.
When you can see the path forward, the stress starts to lift. And in times like these, that clarity is worth its weight in gold.
How I Can Support You
Here’s the truth: a calculator is only as powerful as the person guiding you through it. That’s where I come in. As your mortgage agent, I can:
- Walk you through the Optimizer step-by-step.
- Run advanced scenarios and strategies tailored to your goals.
- Negotiate with lenders to find the best mortgage product for your affordability.
- Coordinate with your realtor to make sure your dream home is also your affordable home.
- Keep you updated on rate changes so you can act when the timing is right.
Bottom line: I’m here to help you not just qualify for a mortgage, but thrive with it. Because in this affordability crunch, it’s not just about keeping a roof over your head—it’s about keeping peace of mind under that roof, too.











