
Every year, about 15% of Canadians refinance their mortgage to take advantage of better mortgage terms (reduced rate, amortization, or mortgage feature), improve their financial condition, buy out a partner, or take advantage of an investment or business opportunity.
While everyone’s personal and financial situation is different, refinancing your mortgage presents unique opportunities you should know are available to you. The following are 10 common reasons Canadians refinance their mortgages.
1. Lower Interest Rates
Reducing Monthly Payments: Homeowners may refinance to secure a lower interest rate, which can reduce their monthly mortgage payments and save money over the life of the loan. Today, it is very common for Canadians to choose to amortize their mortgages from 25 years to 30 years if possible. This can give Canadians more cash in their budget every month to help pay for the things they need.
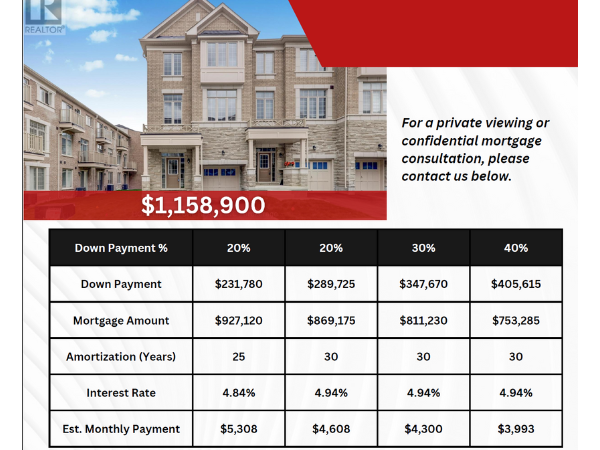
In the above rate sheet, you can see how changing the amortization (the number of years to pay back the mortgage) from 25 to 30 years changes the monthly payment from $5,308 to $4,608 a month.
Switching from Variable to Fixed Rate: Some borrowers refinance to switch from a variable-rate mortgage to a fixed-rate mortgage to lock in a lower rate and gain payment stability. Presently, variable rate mortages are offered at a higher rate than fixed rate mortgages. Variable rate mortgages follow the prime rate of the lender which is higher than the bond yield rate that fixed rate mortgages are aligned with.
2. Accessing Home Equity:
Home Renovations: Many homeowners refinance to access their home equity to fund renovations or upgrades that can increase the property’s value. What’s popular right now is seniors choosing to make their home more ‘senior friendly’ by installing chair lifts, removing bath tubs in favour of showers, installing ramps and making other upgrades to stay in their home through their senior years.
Debt Consolidation: Refinancing to consolidate high-interest debt, such as credit cards or personal loans, into a lower-interest mortgage can help manage debt more effectively. Simplify your life by rolling all your payments into your mortgage and enjoy a much lower overall interest rate saving you thousands of dollars in the process.
Large Purchases or Investments: Some homeowners take out equity to finance large purchases (e.g., a car or vacation) or to invest in other opportunities.
3. Changing Mortgage Terms:
Shortening the Amortization Period: Homeowners might refinance to shorten their mortgage term, enabling them to pay off their home sooner and save on interest payments.
Extending the Amortization Period: Conversely, some may extend the amortization period to reduce monthly payments, providing more financial flexibility.
4. Paying Off or Removing a Co-Borrower:
Divorce or Separation: Refinancing can be necessary to remove a spouse or partner from the mortgage after a separation or divorce.
Buying Out a Co-Owner: Refinancing can also be used to buy out the interest of a co-owner in the property.
5. Switching Lenders for Better Terms:
Securing Better Rates or Terms: Some homeowners refinance to switch to a lender offering better interest rates, more flexible terms, or better customer service.
Accessing Different Mortgage Products: Borrowers might refinance to access a different type of mortgage product that better suits their financial goals, such as a HELOC or a different payment structure.
6. Removing Mortgage Insurance:
Cancelling Mortgage Default Insurance: If the home’s equity has increased significantly, refinancing may allow the homeowner to eliminate the need for mortgage default insurance (CMHC, Sagen, or Canada Guaranty), thereby reducing overall costs.
7. Managing Life Events:
Funding Education or Medical Expenses: Some homeowners refinance to pay for major life expenses, such as a child’s education or unexpected medical bills.
Financial Emergencies: In cases of financial hardship, homeowners may refinance to access cash to cover emergencies or to prevent foreclosure.
8. Improving Cash Flow:
Reducing Payment Obligations: By refinancing at a lower interest rate or extending the mortgage term, homeowners can improve their monthly cash flow.
9. Taking Advantage of Increased Property Value:
Leveraging Appreciation: Homeowners who have seen significant appreciation in their property value might refinance to access the increased equity for other investments or financial needs.
10. Renewing a Mortgage:
Exploring Better Options: When the mortgage term comes up for renewal, some homeowners refinance to explore more favourable terms or to make changes to the mortgage that align with their current financial situation.
How Canadians Refinance Their Mortgage
While there are many reasons for Canadians to refinance their mortgage, there are 4 ways to achieve their goals:
- Cash-out Refinance
- Home Equity Loan (a.k.a Second Mortgage)
- Home Equity Line of Credit
- Reverse Mortgage
See Also:
- Reverse Mortgages and the Affluent Retiree
- Reverse Mortgage: Cushion Against Inflation
- Reverse Mortgage to a Second Dream Home
- Struggling Financially as a Senior
Summary
Refinancing is a strategic financial decision, and homeowners should work with Allen Ehlert to carefully consider their goals, the costs involved, and the potential impact on their long-term financial health before proceeding. Choosing not to refinance may result in losing opportunities to improve your financial security and build your wealth.
As your mortgage agent, I not only help you get the best mortgage product for you based on your goals and your needs, but as your financial professional, I monitor your mortgage against what is going on in the market and let you know when opportunities arise that you can take advantage of.











