… Keep the Rate, and the House
When a marriage ends but the home still makes sense financially and emotionally, the question becomes: how do you keep the house without blowing up the mortgage? One of the most elegant solutions is something called a mortgage assumption with a release of covenant. In plain English, you keep the existing mortgage exactly as it is while removing your former spouse from the legal responsibility.
Sounds simple, right? Well… sometimes it is, and sometimes lenders make you jump through a few flaming hoops to get there.
Still, when it works, this path can save thousands of dollars in penalties and keep a fantastic interest rate intact. Let’s walk through how it actually works, what the numbers look like, and how lawyers, financial planners, and mortgage professionals help make it happen.
How Mortgage Assumption Works in Divorce
First things first: if both spouses signed the mortgage, the lender still sees both of you as responsible for the debt until they formally release one of you. A separation agreement might determine who keeps the house, but it doesn’t automatically change the mortgage contract.
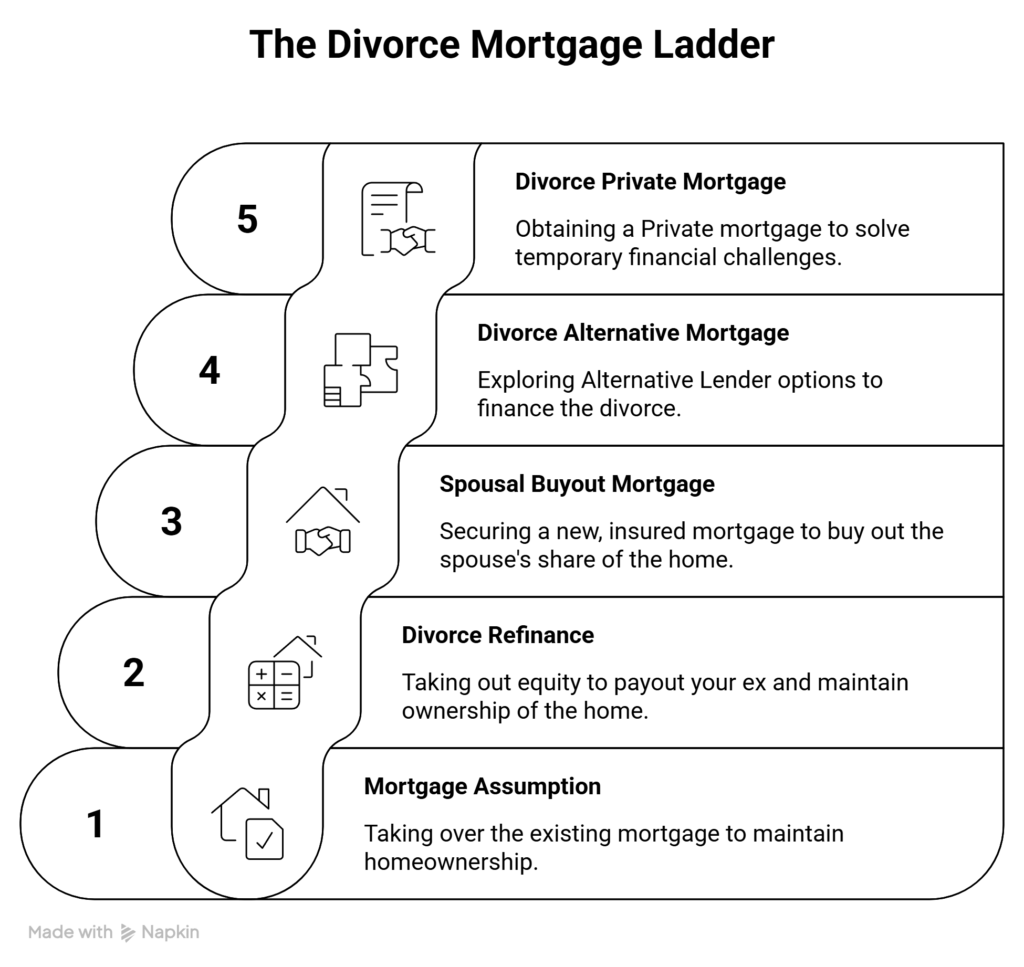
A mortgage assumption allows one spouse to keep the existing mortgage terms while the other spouse is removed from the legal obligation.
Procedure
First, the lender reviews the existing mortgage contract to determine whether it is assumable.
Second, the spouse keeping the home must re‑qualify for the mortgage on their own.
Third, the lender assesses income, debts, credit, and the stress test.
Fourth, a real estate lawyer transfers title into the name of the remaining spouse.
Fifth, the lender issues a formal release of covenant removing the departing spouse from liability.
A Financial Example
Let’s say you and your spouse bought a home several years ago and are now separating. In this scenario, the spouse keeping the home has significantly improved financial strength since the original mortgage was approved. Their income has increased, their credit profile is stronger, and they also hold other accounts with the lender, which reduces perceived risk.
Because the mortgage balance does not need to increase, the lender is comfortable approving a release of covenant and mortgage assumption.
Property and Mortgage Details
Home value: $900,000
Mortgage balance: $480,000
Interest rate: 2.1% fixed
Remaining term: 3 years
At first glance, the equity looks like this:
$900,000 − $480,000 = $420,000 equity
If you simply split the gross equity, each spouse would receive:
$420,000 ÷ 2 = $210,000
But in many divorce settlements, lawyers adjust this number to reflect future selling costs, because if the home were sold later both spouses would normally share those expenses.
Step 1 — Adjust Equity for Future Selling Costs
Estimated selling costs:
Realtor commissions (5%): $45,000
Legal + closing costs: $5,000
Total estimated selling costs: $50,000
Net equity calculation:
$420,000 − $50,000 = $370,000 net equity
Each spouse’s share:
$370,000 ÷ 2 = $185,000
This becomes the buyout payment.
Step 2 — Assumption Transaction Costs
Even though the mortgage is not replaced, there are still some administrative and legal costs involved.
Typical assumption-related costs might look like this:
Legal fees for title transfer and covenant change: $1,200
Mortgage assumption administration fee: $500
Possible appraisal (depending on lender policy): $500
Total assumption transaction costs:
$2,200
Step 3 — Total Cash Needed to Complete the Assumption
Buyout payment to spouse: $185,000
Assumption transaction costs: $2,200
Total required funds:
$187,200
In this example, the spouse keeping the home uses savings or family assistance to fund the buyout and closing costs.
Because the mortgage balance does not increase, the lender may approve the assumption and release the departing spouse from the covenant.
Step 4 — Monthly Payment Comparison
Existing mortgage:
Balance: $480,000
Interest rate: 2.1%
Monthly payment:
Approximately $2,050
If the mortgage had to be refinanced at current rates (example 5.5%):
Monthly payment would rise to roughly:
$2,950
Monthly difference:
$900 per month
That is over $10,800 per year in additional mortgage costs avoided simply by keeping the existing mortgage.
Why This Matters
This example illustrates why mortgage assumptions are often the most financially efficient option when they are available.
The assumption structure avoids many large costs that arise with other divorce mortgage solutions, including:
- mortgage prepayment penalties
- mortgage discharge fees
- new mortgage default insurance premiums
- realtor commissions associated with selling the property
Instead, the main financial components become:
- the negotiated equity buyout
- legal work to transfer title
- lender administrative fees
Practical Insight from the Field
In real divorce negotiations, the difference between gross equity and net equity after sale costs can significantly affect mortgage feasibility.
In the example above, adjusting the buyout from $210,000 to $185,000 reduced the cash requirement by $25,000.
That type of adjustment can sometimes determine whether:
- a mortgage assumption is possible
- a refinance stays under the 80% loan-to-value ceiling
- a borrower must instead pursue a high-ratio spousal buyout mortgage
Small negotiation details often have major mortgage consequences.
A Story from the Field
A client once told me, “Allen, if I lose this rate, I lose the house.”
She had locked in during the ultra‑low interest era. Her separation agreement required a buyout, but she had family help for the equity payout.
We approached the lender with a clean assumption application. Because her income was strong, her financial picture had improved substantially, and the loan balance remained unchanged, the lender approved the release.
Her ex walked away cleanly. She kept the house. And she kept a rate most Canadians would love to have today.
How Professionals Put This Strategy to Work
Lawyers use this option when drafting separation agreements. If assumption is possible, they structure the agreement so equity can be paid without increasing the mortgage.
Financial planners often help clients reposition assets so the buyout can be funded without refinancing.
Accountants may help evaluate tax implications when investments are liquidated to fund the buyout.
Realtors sometimes help clients evaluate whether keeping the home still makes sense financially.
Allen’s Final Thoughts
Mortgage assumptions are the golden ticket in divorce mortgage planning. When they work, they protect a great interest rate and avoid expensive penalties.
But lenders are cautious. They must be confident that the remaining borrower can handle the loan independently.
That’s where I come in.
As a mortgage agent, I review your existing mortgage contract, communicate with the lender, run qualification scenarios, and coordinate with your lawyer and financial team.
My job is to help you keep the house if it makes sense—and to build a mortgage structure that actually supports your life after divorce.
See Also
Refinance to Buy Out Your Ex
Spousal Buyout as a Purchase