
… Inside the Black Box of Mortgage Lending and Real Estate Finance
Most Canadians think mortgages are simple. You walk into a bank, talk to someone behind a desk, sign some papers, and that’s that. Clean. Simple. Straightforward.
That’s so yesterday!
But the truth—one that rarely gets talked about—is that mortgage lending and real estate finance operate very much inside a black box. What you see on the surface is only a small slice of what’s actually happening behind the curtain. You are looking at the tip of the iceberg. This becomes even more true the moment you step outside traditional banks and into the world of shadow banking and private mortgages.
Allow me to give you a glimpse.
What I’ll Cover
Why Mortgage Lending Operates Like a Black Box
Where Private Mortgages Fit In
Why Banks Say No—and Others Say Yes
How Realtors Use This Knowledge Strategically
A Story From Inside the Black Box
How to Navigate Shadow Banking Safely (Step-by-Step)
What Is Shadow Banking
Shadow banking sounds dramatic—and honestly, the name doesn’t help—but it simply refers to non-bank lending. These are lenders that don’t take deposits like traditional banks, but still provide mortgages and real estate financing.
In Canada, shadow banking includes:
- Monoline mortgage lenders
- Trust companies
- Alternative (“B”) lenders
- Private lenders and Mortgage Investment Corporations (MICs)
Many Canadians, about half, already have mortgages funded through shadow banks without realizing it. If your mortgage isn’t with a Big Six bank, there’s a good chance you’re already in this ecosystem.
Shadow banking exists because banks are designed for the middle of the bell curve. People who have never been divorced, been at a stable government job for more than 5 years, have a sizeable down payment, and purchase a large, modern home in a stable neighbourhood within a reasonably large urban centre.
Today, that’s not most people. Real life doesn’t look like that. Shadow banking is for everyone else; even if they don’t know it.
Why Mortgage Lending Operates Like a Black Box
From the outside, mortgage approvals look binary: approved or declined. What borrowers don’t see is the web of policies, risk models, lender appetites, capital structures, and internal rules that drive those decisions.
Two borrowers with identical incomes can get wildly different answers depending on:
- How income is calculated
- How risk is priced
- Which lender is reviewing the file
- What capital backs the loan
None of this is visible to the public.
Lenders don’t explain why one rule applies and another doesn’t. And those rules at each lender are constantly changing for dozens of reasons. Private lenders don’t advertise how they assess risk. Investors don’t see borrowers, and borrowers never meet investors, let alone their BDMs.
That’s the black box.
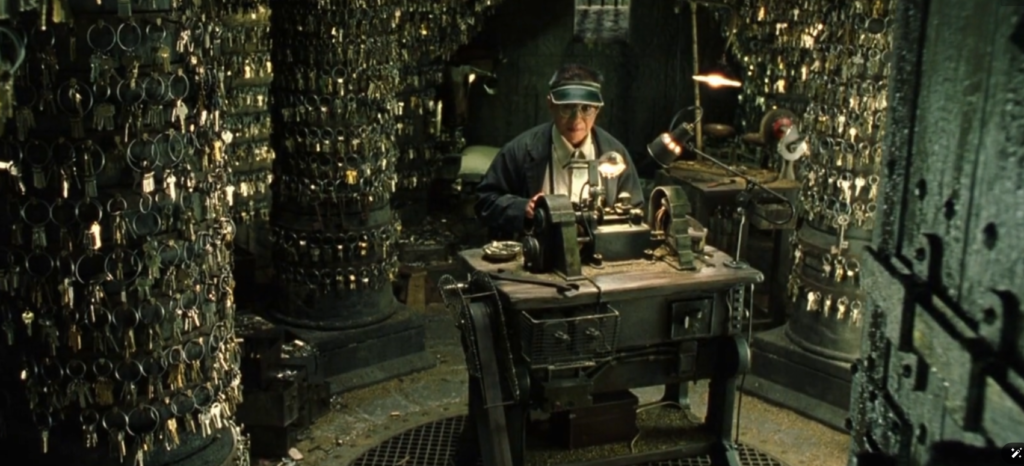
I’m the key maker. The one who stands at the doorway between these worlds.
Where Private Mortgages Fit In
Private mortgages are the deepest part of the box. Think of them as the black box within the black box. Private mortgages are an increasingly critical part of our ‘hidden’ financial system because:
- They provide liquidity when the system freezes
- They price risk instead of rejecting it
- They act as a financial transition or bridge
- They keep real estate markets functioning
- They support real-world complexity
- They solve difficult problems
They are funded by individual investors or pooled investor capital rather than institutions. Because of that, decisions are:
- Faster
- More flexible
- More expensive
Private lenders don’t ask, “Does this fit policy?” They ask, “Is this risk worth the return?”
That shift—from policy-based lending to risk-based lending—is why private mortgages can exist where banks cannot.
Used correctly, private lending is a bridge to freedom. Used incorrectly, it’s a dangerous trap.
Why Banks Say No—and Others Say Yes
When a bank declines a mortgage, it’s rarely personal. It’s mechanical.
Banks are constrained by:
- Federal regulation
- Capital requirements
- Internal risk limits
- Reputation risk
Shadow banks and private lenders are constrained by something else entirely: pricing and structure.
They don’t eliminate risk—they charge for it.
That’s why borrowers who are self-employed, recently divorced, credit-repairing, or investing often find solutions outside the banking system. That’s why developers who need access to capital in a timely fashion without a mountain of documents turn to private lenders. It’s why companies, business, and those in the commercial space lean on private lending to engineer solutions.
How Realtors Use This Knowledge Strategically
Top realtors understand that financing is the weakest link in most transactions.
Working with me, we’ll use shadow banking knowledge to:
- Keep deals alive when bank financing fails
- Advise clients realistically on timelines
- Structure offers with confidence
- Avoid last-minute collapses
Knowing that a solution exists—and knowing how it works—are two very different things.
That’s where the right mortgage agent becomes indispensable.
A Story From Inside the Black Box
A buyer once came to me after being declined by two banks. Strong income. Large down payment. Great property.
The problem? Their income didn’t fit neatly into any lender’s formula.
Instead of forcing the file through a brick wall, we stepped sideways. A short-term private mortgage allowed the purchase to close while income was properly documented and averaged. Twelve months later, we exited cleanly into a prime lender.
Same borrower. Same house.
Different lens.
How to Navigate Shadow Banking Safely (Step-by-Step)
Shadow banking works best when there’s a plan. Here’s my broad approach:
- First, understand why bank financing isn’t available right now
- Second, choose the least expensive, least risky alternative
- Third, structure terms around a clear exit strategy
- Fourth, document the path back to prime lending
- Finally, reassess regularly and adjust as circumstances change
Shadow banking should always answer one question: What’s next?
Allen’s Final Thoughts
Shadow banking isn’t dangerous because it’s hidden. It’s dangerous when people don’t understand it.
The mortgage and real estate finance world runs on rules businesses and consumers never see. That doesn’t make it broken—it just makes guidance essential.
My role is to open the door to black box and be your eyes in the darkness. To explain what lenders won’t. To show you the levers, inform you of the risks, and guide you to the exits—before you commit.
Whether you’re a buyer trying to make a deal work, a homeowner navigating change, or a realtor protecting a transaction, I’m here to help you use the full financial system intelligently—not blindly.
No fear. No mystery. Just informed strategy.











