
… When You Can’t Simply Refinance
Sometimes divorce math simply doesn’t cooperate.
You want to keep the house, the monthly payment is manageable, but the refinance limit of 80% stops the deal from working.
That’s where the spousal buyout purchase structure comes into play.
Think of it as a pressure‑release valve in the mortgage system.
Instead of treating the transaction as a refinance, lenders treat it like a purchase where you are buying your ex‑partner’s share of the property.
That simple shift can dramatically increase borrowing capacity.
How the Spousal Buyout Mortgage Works
In Canada, high‑ratio mortgages can be insured by organizations like CMHC, Sagen, or Canada Guaranty. Mortgage default insurance allows lenders to finance up to 95 percent of a property’s value. It works like this:
First, the transaction is structured as a purchase of the departing spouse’s interest.
Second, the lender orders an appraisal.
Third, the mortgage insurer reviews the application.
Fourth, the borrower qualifies under the stress test and standard underwriting.
Fifth, the lawyer transfers title and distributes the equity payout.
Financial Example
Let’s consider a situation where the spousal buyout is required because of a 92% loan to value (LTV). Here, the spouse keeping the home wants to maintain continuity for the children — keeping them in the same school and community.
However, the buyout amount pushes the mortgage above the 80% refinance ceiling.
The only way to finance the buyout is through an insured spousal buyout purchase.
Property and Mortgage Situation
Home value: $900,000
Existing mortgage: $728,000
Equity: $172,000
Each spouse share: $86,000
Mortgage required:
$728,000 + $860,000 = $814,000
814,000 ÷ 900,000 = 90.4%,… let’s adjust this to 92% for our example.
This falls within high-ratio lending and requires mortgage insurance.
Insurance premium (approx 4%): $33,120
Mortgage including premium: $861,120
Ontario PST on premium: $2,560
(must be paid at closing and cannot be added to the mortgage).
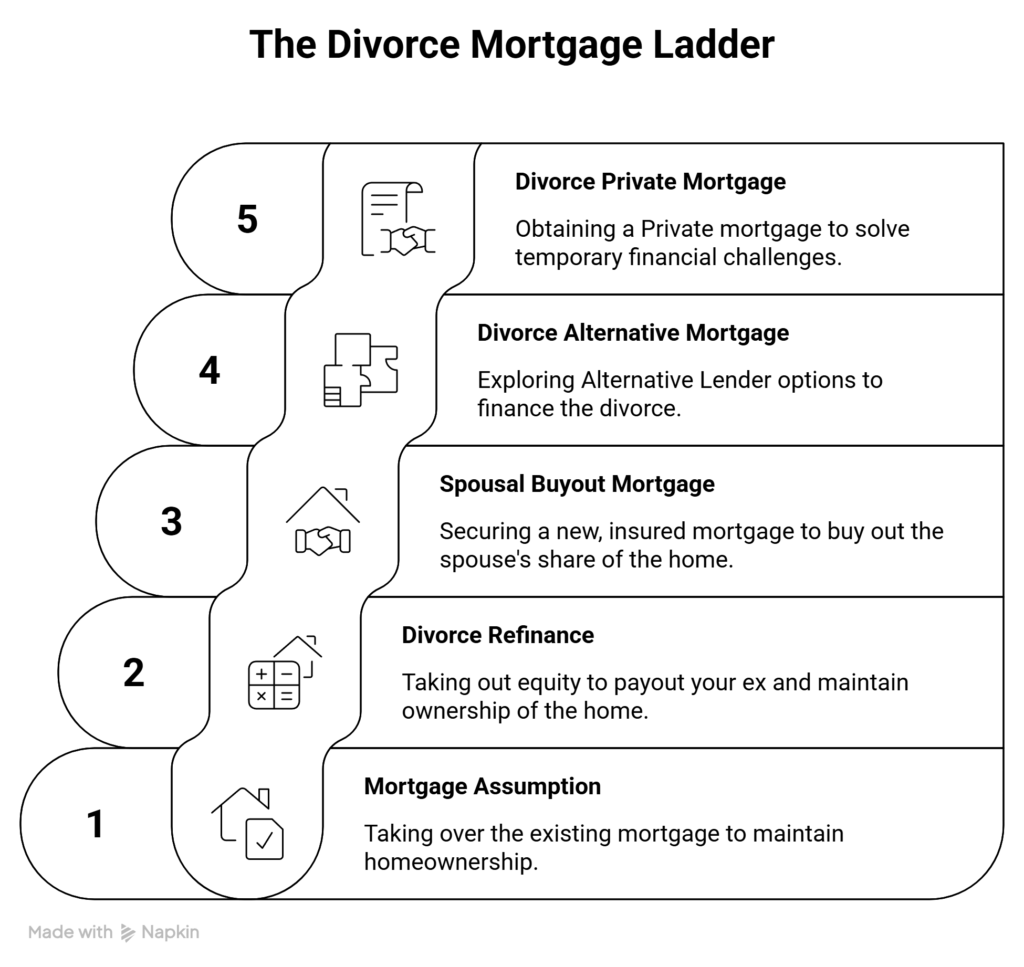
Comparison of Divorce Paths
| Category | Mortgage Assumption | Refinance Buyout | Spousal Buyout (Insured Purchase) |
| Property value | $900,000 | $900,000 | $900,000 |
| Mortgage required | $728,000 | $828,000 | $828,000 |
| Loan-to-value | 81% | 92% (exceeds 80% refinance cap) | 92% |
| Interest rate example | 2.3% | 5.4% | 5.2% |
| Monthly payment | $3,200 | $5,060 | $5,150 |
| Mortgage penalty | None | $15,000 | $15,000 |
| Mortgage insurance premium | None | Not available | $33,120 |
| PST on premium (Ontario) | None | N/A | $2,650 |
| Legal fees | $1,200 | $2,000 | $2,000 |
| Appraisal | $500 | $500 | $500 |
| Estimated closing costs | $1,700 | $17,500 | $53,270 |
| Feasibility | Very unlikely | Fails refinance rules (>80% LTV) | Best solution in this scenario |
Best Option
Spousal Buyout (Insured Purchase)
Even though it involves mortgage insurance, it is the only structure that allows the borrower to reach the required loan-to-value and keep the home.
An Example Story
A client once said to me, “Allen, if I have to sell this house, my kids lose their childhood home.”
Their refinance option had failed because the buyout exceeded 80 percent of the property value.
Using a spousal buyout insured mortgage, was the best way to restructure the deal.
The insurance premium added cost, but it allowed the client to keep the home and maintain stability for the family.
Sometimes that’s worth every penny.
How Professionals Put This Strategy to Work
Family lawyers often negotiate settlements assuming the spousal buyout structure is available.
Financial planners incorporate the insurance premium into long‑term financial planning.
Accountants evaluate the cash flow impact of the larger mortgage.
Realtors help clients understand whether the home remains financially sustainable.
Allen’s Final Thoughts
The spousal buyout purchase strategy is often the difference between selling a home and keeping it.
It allows financing up to 95 percent loan‑to‑value, which can unlock solutions when refinance limits block the path.
Yes, the mortgage insurance premium adds cost.
But for many families, the ability to keep the home during a difficult life transition is priceless.
My role as your mortgage agent is to run the scenarios, identify which lenders support equity buyouts, and coordinate the financing with your lawyer and financial advisors.
Divorce is already complicated enough.
My job is to make the mortgage side of it clear, structured, and manageable.
See Also
Transfer and Assumption with Release of Covenant
Refinance to Buy Out Your Ex











