
A Home Equity Line of Credit is often pitched as simple, harmless, even boring. “You’re pre-approved.” “You don’t have to use it.” “It’s there just in case.”
Sounds reasonable. Comforting, even.
But here’s what almost no one tells you up front: a HELOC is not a commodity, and it’s not a neutral product. It’s a powerful, complex financial instrument that behaves very differently depending on who you are, how it’s structured, and who helped you set it up.
That’s exactly why where you get your HELOC matters just as much as whether you get one at all.
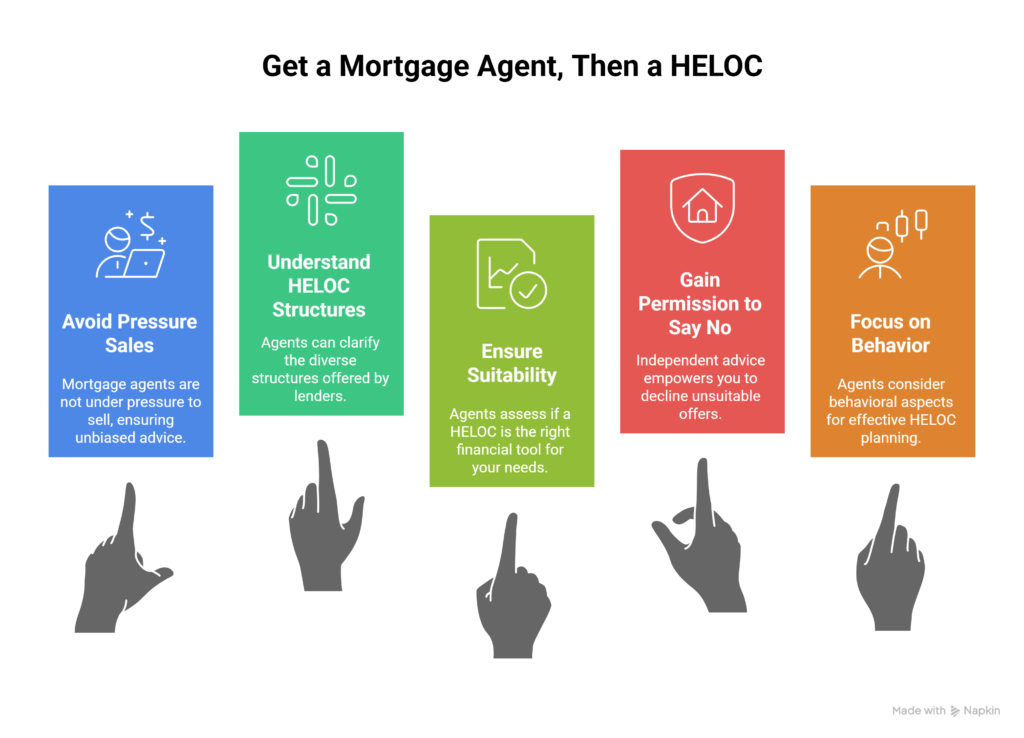
Before we dig in, here are the core reasons working through a mortgage agent changes the outcome:
- Most HELOCs are sold by people under pressure to sell them
- A HELOC is not a HELOC—structures vary wildly by lender
- Qualification does not equal suitability
- Independent advice creates permission to say “no”
- Good HELOC planning is behavioural, not just mathematical
Let’s walk through this slowly and honestly.
Most HELOCs Are Sold by People Under Pressure to Sell Them
This is the part most consumers don’t realize—and most institutions won’t say out loud.
When you discuss a HELOC inside a bank branch or call centre, you’re almost always speaking to a product salesperson, not an independent advisor. They may be experienced. They may be helpful. But they are still operating within a system built around targets, campaigns, and growth metrics.
Ask yourself a simple question:
What is the likelihood that someone measured on product penetration is going to say,
“This HELOC isn’t right for you. You shouldn’t do this.”
It’s not impossible—but it’s unlikely.
Their job is to tell you:
- You qualify
- It’s flexible
- It’s cheaper than other debt
- You don’t have to use it
All technically true.
Also dangerously incomplete.
What often goes unexplored is whether this tool actually improves your financial life—or quietly increases risk.
A HELOC Is Not a HELOC—Structures Vary Wildly by Lender
This is where independent advice becomes critical.
A HELOC can differ dramatically depending on the lender:
- Standalone HELOC vs. readvanceable mortgage
- Fixed limits vs. dynamically increasing limits
- How aggressively lenders monitor credit and property values
- How easily access can be frozen
- Pricing spreads over prime
- Options (or restrictions) for locking into fixed rates
- Standard vs. collateral charges and future switching friction
Two people can both say, “I have a HELOC,” and be living in completely different financial realities.
A mortgage agent compares these structures across lenders, not just inside one institution’s product shelf. That’s the difference between choosing a tool and being handed one.
Qualification Does Not Equal Suitability
Banks are excellent at answering one question:
“Can this borrower qualify?”
Mortgage agents are paid to ask a harder one:
“Should this borrower have this product at all?”
Those are not the same thing.
A HELOC amplifies behaviour. If you’re disciplined, it can be a quiet safety net. If you rely on optimism, convenience, or thin margins, it can quietly turn into a trap.
Inside a product-driven environment, suitability conversations are short. With an independent mortgage agent, they’re the entire point.
Independent Advice Creates Permission to Say “No”
Here’s the quiet advantage of working with someone like me:
I don’t have a HELOC to sell you.
I don’t work for one lender.
I don’t have quarterly targets.
I don’t get paid more if you borrow more.
That means I can say things like:
- “This flexibility will hurt you, not help you.”
- “You qualify—but you shouldn’t do this.”
- “A smaller line is safer.”
- “The best HELOC for you might be none at all.”
Salespeople rarely get rewarded for slowing things down.
Independent advisors exist to do exactly that.
Good HELOC Planning Is Behavioural, Not Just Mathematical
Most HELOC conversations focus on:
- Rates
- Limits
- Approval
The conversations that actually prevent regret focus on:
- How you behave with revolving credit
- How you react when rates rise
- Whether flexibility calms you or tempts you
- What happens when income dips or plans change
These aren’t box-checking questions. They require context, pattern recognition, and experience watching how HELOCs play out over time.
That’s the lens I bring to the table.
A Real-World Story That Says It All
I once worked with two homeowners with nearly identical profiles on paper.
Both qualified easily.
Both had significant equity.
Both were offered HELOCs by their banks.
One borrower used the line sparingly—six months of income disruption, paid it back, moved on. No drama.
The other used their HELOC repeatedly to chase opportunity. More property. More leverage. Thin margins. Optimism instead of buffers.
When rates rose and markets cooled, the second borrower was forced to consider selling their home at a price the market would no longer support—simply because the HELOC balance had grown too large.
Same product name.
Completely different outcomes.
The difference wasn’t intelligence.
It was structure, behaviour, and advice.
What This Looks Like in Practice
For realtors
- Encourage clients to get HELOC advice before they commit to leverage
- Flag layered-debt risks early
- Avoid framing HELOCs as “standard tools everyone should have”
For clients
- Treat HELOCs like loaded tools, not conveniences
- Demand a conversation about downside, not just approval
- Work with someone who can compare options—and say no
How I Help You Get This Right
When someone comes to me about a HELOC, my role isn’t to open a line—it’s to protect future you.
I help clients:
- Decide whether flexibility or constraint suits them better
- Compare HELOC structures across lenders
- Understand freeze risk, pricing risk, and exit risk
- Model rate shocks and stress scenarios
- Build rules and exit strategies before a dollar is drawn
Sometimes the answer is yes.
Sometimes it’s smaller.
Sometimes it’s not at all.
All three can be good advice.
Allen’s Final Thoughts
A HELOC can be a brilliant safety net—or a slow-burn financial problem. The difference usually isn’t the rate. It’s who helped you decide in the first place.
When HELOCs are sold, the conversation ends at approval.
When HELOCs are advised, the conversation begins with behaviour, structure, and long-term consequences.
If you’re going to tie your home to a line of credit, you want someone in your corner who isn’t trying to move product—but trying to reduce regret.
That’s what I do.
Not because HELOCs are bad—but because they’re powerful.
And powerful tools deserve independent advice.











