
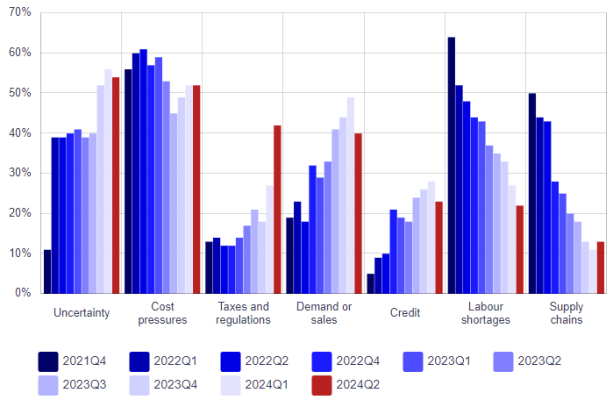
According to the Bank of Canada’s report, uncertainty and cost pressures remain firms’ most frequently mentioned concerns. The sources of uncertainty were domestic factors:
- Economic growth
- Interest Rates
- Tax Policies
- Declining business sentiment
- Consumers cut back on spending
- Excess supply of labour
- Declining wage and salary growth
- Canadians still have a home purchase as their primary financial goal
This uncertainty is contributing to businesses’ modest investment plans.
Government Taxes and Regulation
The share of firms citing taxes and regulation as one of their top concerns increased sharply this quarter. Firms mentioned red tape and regulations as slowing their plans, and taxes, predominantly the carbon tax, as increasing their costs.
Meanwhile, capacity pressures—namely labour shortages and supply chain challenges—have continued to decline in importance over the past two years. And for the first time since the start of 2023, demand has become less of a concern.
Question: Which Issues Have Been the Most Pressing for Your Company?
Weak Sales Growth Expectations
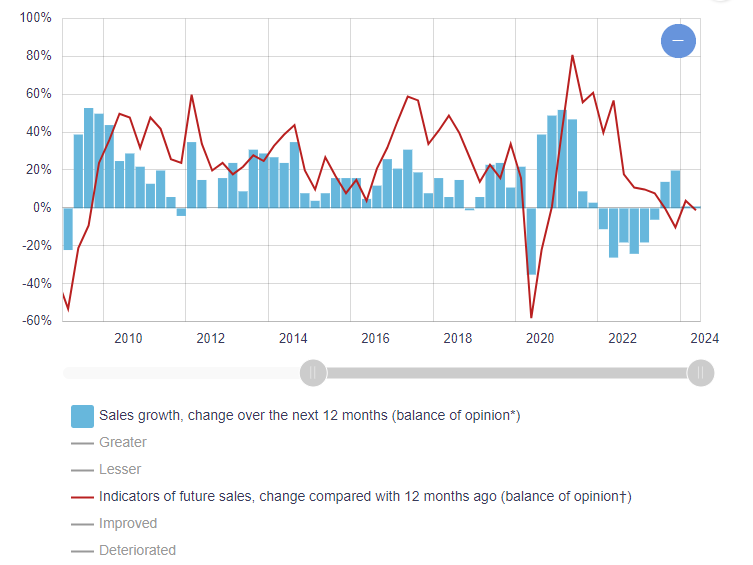
Firms reported below-average sales growth over the past 12 months and continue to expect soft demand going forward. Businesses’ indicators of future sales (e.g., order books, advance bookings, sales inquiries) are largely unchanged over the past four quarters, with the balance of opinion remaining historically low.
Further, firms expect no change in the pace of their sales growth. At the time, they see interest rate cuts ahead—a view increasingly widespread among firms. Most said they expect rates to decline by 0.5–1.0 percentage points in the next 12 months. However, they noted they still see the interest rate environment as weighing on their sales outlooks.
Question: Is Your Firm’s Sales Volumes Expected to Increase, lessen, or stay the same?
Interest Rates Make Canadians Feel Worse Off
Canadians continue to feel the negative impacts of elevated inflation and high interest rates on their financial situation. Almost twice as many consumers reported greater impacts from inflation than from interest rates.
Consumers continue to report taking or planning to take various actions in response to inflation and interest rates, with the most cited actions being:
- Reducing spending
- Paying off debt
- Moving savings to accounts with higher interest rates
- Increasing household income
When asked, “Were you financially impacted by recent Bank of Canada increases in interest rates or by recent higher inflation?”, Canadians responded:
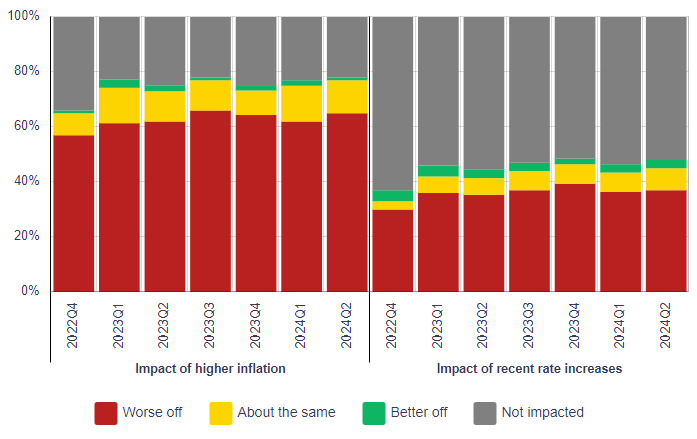
More Canadians feel the effects of higher inflation than of recent interest rate increases. This makes sense, as everyone feels the impact of inflation but only those with a mortgage feel the impact of recent rate increases.
Business Sentiment Declines
The Business Outlook Survey from the Bank of Canada reports that business sentiment in Canada is declining.
Overview:
- Firms’ sales outlooks remain more pessimistic than average.
- Businesses tied to discretionary spending reported particularly weak sales
- Investment spending plans also remain below average.
- Weak demand, elevated interest rates, uncertainty about the business environment, and the high cost of machinery and equipment were cited as discouraging investment.
- Firms reporting labour shortages is low
Business Conditions Subdued
After recovering from the lows seen in late 2023, business sentiment remained relatively flat in the second quarter of 2024. When discussing factors weighing on business sentiment, firms mentioned:
- Elevated Interest Rates
- Weak demand, particularly for non-essential goods and services
- Ongoing high costs
Question: How Would You Rate Current Business Conditions for Your Firm?

At the same time, though, the share of firms planning for a recession in Canada in the coming 12 months continued to decline.
Question: Do You Expect a Recession Over the Next 12 Months?

Where’s the Labour Shortage?
The Business Outlook Survey conducted by the Bank of Canada for the spring of 2024 found new firms face labour shortages.
Businesses across all regions and sectors reported that the labour market has continued to ease. The share of firms citing labour shortages is near survey lows. For the sixth consecutive quarter, firms noted the intensity of labour shortages had lessened.
Businesses said this widespread easing is driven by:
- Soft sales expectations leading to less demand for additional workers
- An increased supply of workers due to immigration
These factors will keep wages and salaries down and below those offered in the United States. This condition will continue to challenge many of the affordability issues faced by Canadians.
The labour shortages that do remain are mostly related to structural issues in certain parts of the labour market, such as specialized skills in remote locations.
Question: Does Your Firm Face Any Shortages of Labour Impacting Your Ability to Meet Demand?

Given this widespread easing in the labour market, firms’ expectations for wage increases in the next 12 months have softened. The average expected wage increase in the next 12 months has declined significantly. An increasing share of firms expect the pace of wage growth to slow in the next 12 months. On balance, firms no longer see a need for higher wages to attract or retain workers. Notably, firms see less pressure on wages from:
- cost-of-living increases
- a need to raise wages to match the market wage
Moreover, firms said their own performance and profitability continue to be a constraint on their wage increases. Still, the average wage point estimate is slightly above its historical average as new union contracts come into effect and some pass-through of previous cost-of-living increases continues.
Wage Expectations
Question: Are Increases in Labour Costs Expected to be Higher, Lower, or the Same Over the Next 12 Months?

We can expect wage and salary costs to fall below the rate of inflation going into 2025 which will make life more difficult for the average working Canadian.











