There was a time when buying a home was as simple as flipping through a real estate magazine, picking a house, and heading to the bank with little more than a job letter and a pay stub. But today’s mortgage landscape is vastly different.
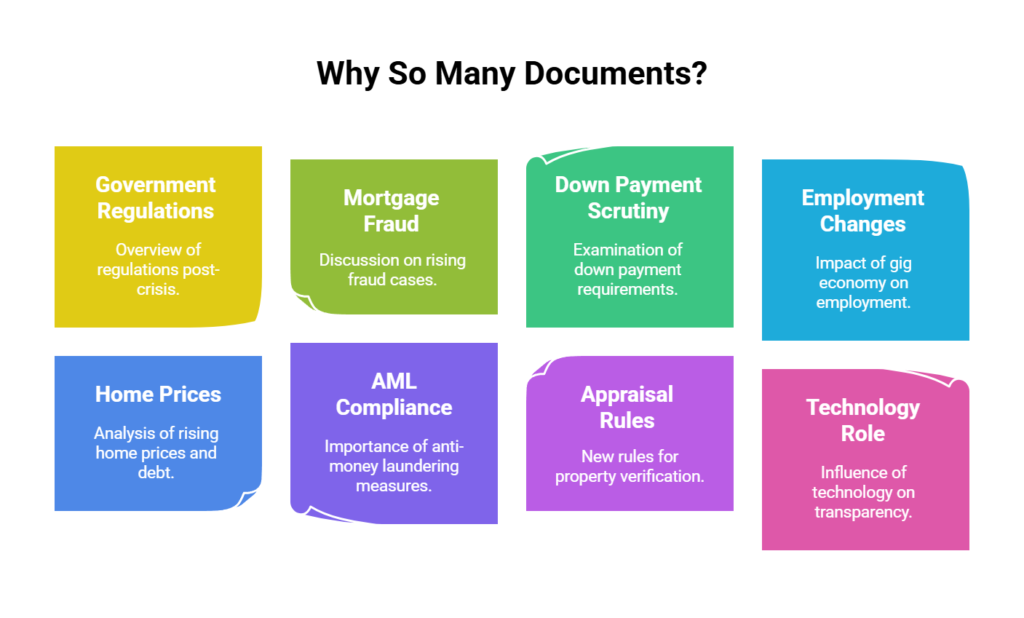
Modern mortgage underwriting requires applicants to provide extensive documentation—six or seven times what was required 20 years ago. This shift is due to a combination of financial crises, stricter regulations, risk management measures, fraud prevention, and the evolving nature of employment. While it may seem like a burden, these extra steps ensure that lenders make responsible lending decisions, ultimately protecting both borrowers and financial institutions.
If you’re serious about homeownership, preparation is key. Getting organized before you start house hunting can save time, reduce stress, and increase your chances of mortgage approval. Here’s how you can efficiently gather and store your mortgage documents.
See this article to learn more: Why So Much Documentation?
Organizing and Storing Your Documentation
Organizing and Storing Your Documentation
It’s time to get organized and channel your inner accountant! As a mortgage underwriter, I can’t stress enough the importance of organization.
You need a 2-part strategy when it comes to organizing your important documentation because some information is in a digital form and some on paper. And often it is wise to print out a copy or two of your important digital documents as some lenders may require paper copies.
Digital Documents
Use a cloud storage service like Google Drive, Dropbox, OneDrive, or Evernote to store all mortgage-related documents. Organize them into labelled folders such as:
- Income Documents (Pay stubs, T4s, NOAs)
- Employment Verification (Letter of employment, work contracts)
- Down Payment Documents (Bank statements, gift letter, investment statements)
- Credit & Debt Information (Credit report, loan statements)
- Property Documents (MLS listing, purchase agreement, appraisal, property tax bill)
- Mortgage Pre-Approval & Correspondence (Pre-approval letter, lender emails)
- Legal Documents (Divorce and Separation Agreements, Power of Attorney, etc.)
Tip: Use file-naming conventions like “2024-T4-[Your Name].pdf” for easy searchability.
I use a similar approach when underwriting a client’s mortgage. For each borrower, I create a collection of folders in a secure portal where I can safely store and organize client documents. This helps me be well organized and allows me to quickly identify if a document is missing so I can follow up with a client.
When you apply for a mortgage, you’ll be asked to upload your mortgage documents securely to a portal that protects your important information using SOC 2 Type 2 compliance protocol. This way, you can be sure your information is protected and secure.
Paper Documents
It often makes sense to have a physical copy of an important document as well as a digital one. Alternatively, we sometimes get a document in the mail that we need to store.
Getting a simple expanding file folder with labelled sections can keep hard copies accessible and organized. This way you can have all of your paper documents in one place so when you are asked to produce them you’ll be able to do so easily.
Creating a Habit of Organization
Staying organized isn’t just about setting up a system—it requires discipline. Each time a new document arrives (whether electronically or in the mail), file it immediately. Whether you’re saving it in your cloud folder or placing it in your file folder, consistency is key.
Set Reminders:
- Update your bank statements every month.
- Request new employment letters before they expire (most lenders require them to be less than 30 days old).
- Check your credit report annually for accuracy.
Avoid Common Mistakes:
- Submitting incomplete documents
- Providing outdated statements
- Mixing personal and business finances (for self-employed borrowers)
Why This Matters
A well-organized borrower makes for a strong mortgage application. When lenders see that your documentation is complete, up-to-date, and neatly structured, they are more likely to process your application smoothly and efficiently.
By taking the time to prepare your documents before you apply for a mortgage, you’ll not only speed up the approval process but also improve your chances of securing the best mortgage terms.
Final Thought: Mortgage rules may have changed, but with the right preparation, buying your dream home doesn’t have to be a stressful experience.
If you’re ready to apply for a mortgage, start gathering your documents today! Have questions about a specific document? Feel free to ask—I’m happy to help!