A mortgage is more than a simple loan—it’s a long-term financial commitment requiring meticulous documentation. Ensuring every piece of paperwork is in order accelerates approvals, improves financing terms, and minimizes stress during the home-buying process.
Proper preparation means you won’t be caught off guard when a lender requests an additional document just days before closing.
Two decades ago, getting a mortgage in Canada was relatively simple. Applicants typically needed only a job letter and a pay stub to secure financing. Fast forward to today, and the process has become significantly more complex, requiring extensive documentation related to income, credit history, debt obligations, down payment sources, and even lifestyle factors.
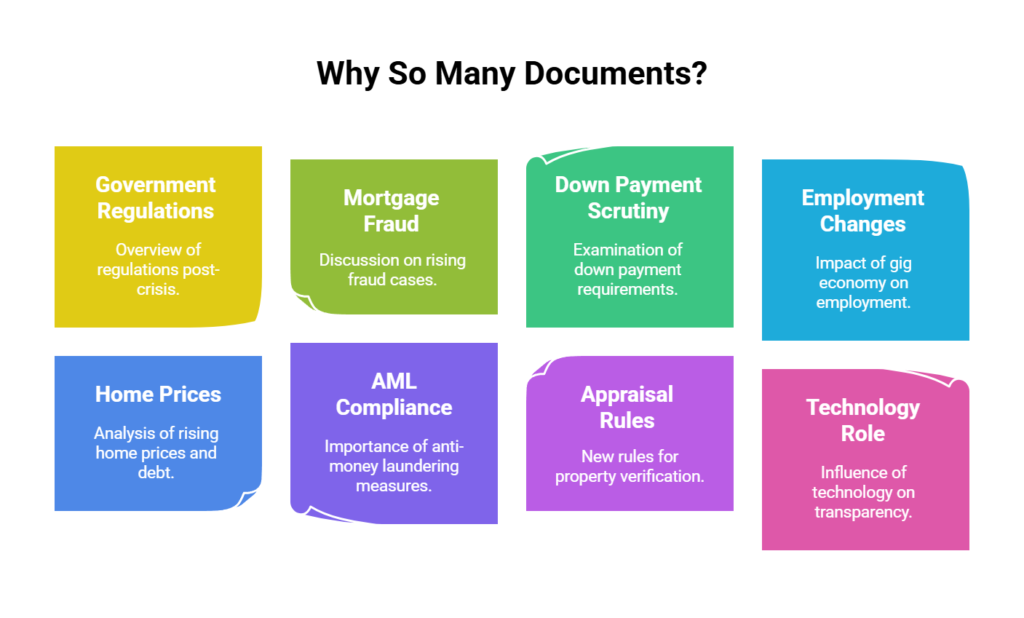
So, what changed? Why do lenders now demand so much more paperwork? The shift can be attributed to economic volatility, regulatory tightening, fraud prevention measures, and evolving lending practices. Let’s explore the key reasons behind these heightened requirements.
The 2008 Financial Crisis & Global Banking Reforms
Government Regulations & Stress Tests
Rising Mortgage Fraud & Document Manipulation
Changes in Employment Structures & Gig Economy Growth
Rising Home Prices & Debt Levels
Anti-Money Laundering (AML) Compliance & Down Payment Scrutiny
Stricter Appraisal & Property Verification Rules
The Role of Technology & Data Transparency
The 2008 Financial Crisis & Global Banking Reforms
One of the biggest turning points in mortgage lending occurred with the 2008 global financial crisis. While Canada’s banking system remained relatively stable compared to the U.S., the crisis exposed vulnerabilities in lending practices worldwide.
What Happened?
- In the U.S., excessive subprime lending led to a housing market collapse, forcing millions of homeowners into foreclosure.
- Many borrowers had stated income mortgages (no proof of earnings required), which contributed to loan defaults.
- Global banks tightened lending criteria to prevent similar collapses in the future.
Impact on Canada
- The Canadian government introduced stricter lending rules to prevent risky borrowing.
- Lenders now require comprehensive proof of income, debt levels, and borrower stability before approving mortgages.
- More detailed income verification (T4s, NOAs, bank statements, etc.)
- Stricter stress testing (ensuring borrowers can handle rate increases)
- Tighter oversight on self-employed and variable-income applicants
Government Regulations & Stress Tests
The Canadian government, through the Office of the Superintendent of Financial Institutions (OSFI), has continuously introduced stricter mortgage qualification rules.
The Stress Test (B-20 Guidelines):
- Introduced in 2018, this rule requires buyers to qualify at a rate 2% higher than their contract mortgage rate.
- Even if a borrower secures a mortgage at 5%, they must prove they could afford it at 7%.
Why This Matters
- More income verification is required to ensure borrowers can handle rising interest rates.
- Lenders need detailed documentation to prove a borrower’s income is stable and sufficient under stress-tested conditions.
- Lenders analyze full debt obligations (car loans, student loans, credit cards).
- Self-employed borrowers must show multiple years of stable income rather than just recent pay stubs.
Rising Mortgage Fraud & Document Manipulation
Mortgage fraud has become a growing concern in Canada. In the past, lenders relied heavily on employer job letters and pay stubs, which were easier to falsify.
Common Types of Mortgage Fraud Today:
Fake Income Documents – Some applicants provide altered pay stubs or fabricated job letters.
Undisclosed Debts – Some borrowers try to hide liabilities to appear more creditworthy.
Straw Buyers – An applicant buys a home on behalf of someone else who wouldn’t qualify.
How Lenders Responded:
- They now require CRA Notice of Assessments (NOAs) to verify income directly from tax filings.
- Additional verification checks, such as bank statements, direct employer contact and verification, and credit bureau cross-checking, have become mandatory.
Down Payment Scrutiny
Two decades ago, it was common for borrowers to provide a personal statement about their down payment source, and that was often enough.
Today, lenders are required to verify exactly where down payment funds come from to prevent money laundering and fraud.
Regulations from FINTRAC (Financial Transactions and Reports Analysis Centre of Canada) now mandate that banks and lenders track large financial movements.
New Down Payment Documentation Requirements:
- 90-day bank statement history to track funds
- Gift letters if money comes from family (ensuring it’s not a loan)
- Additional documentation for borrowed down payments or investments
These stricter policies prevent illicit funds from entering the housing market and ensure that borrowers truly have the savings they claim.
Changes in Employment Structures & Gig Economy Growth
Twenty years ago, most people had stable, full-time salaried jobs with predictable incomes. Lenders could easily verify employment with a letter from HR and a pay stub.
Today, self-employment, gig work, and commission-based jobs are far more common. This shift makes it harder for lenders to assess income stability, leading to stricter documentation requirements for these borrowers.
What’s Changed?
- In 2000, most workers had stable, employer-backed salaries with predictable pay stubs.
- Today, more than 15% of Canadians are self-employed, and thousands more rely on freelance or commission-based income.
How Lenders Adapted:
- Self-employed borrowers must provide two years of tax returns (T1 Generals) and audited business financials.
- Gig workers must prove income consistency over multiple years rather than just recent pay stubs.
- More scrutiny is applied to bonus, overtime, and fluctuating income streams.
- Two years of tax returns (NOAs) instead of just recent income statements
- Bank statements showing consistent business deposits
- Accountant-prepared financials for business owners
- Without this documentation, lenders cannot verify future income stability, making mortgage approvals far more difficult for self-employed individuals.
Rising Home Prices & Debt Levels
Housing affordability has changed dramatically in the past two decades.
Lenders have become far more cautious about a borrower’s total debt obligations compared to 20 years ago. In the past, they primarily looked at income and ignored many other financial liabilities.
Then vs. Now:
- In 2003, the average home price in Canada was around $200,000.
- In 2023, the average home price exceeded $700,000, and in markets like Toronto and Vancouver, it’s well over $1M.
Why Lenders Are More Cautious
- Mortgage loan sizes are now significantly larger, meaning lenders take on more risk per borrower.
- Debt-to-income (DTI) ratios have increased, making it crucial for lenders to assess whether applicants can handle long-term financial commitments.
Additional Documentation Now Required:
- Detailed debt disclosures (credit card statements, car loans, student loans, etc.)
- More stringent down payment verification to ensure funds are not borrowed fraudulently.
Borrowers with high credit card balances are seen as higher risk.
This means more documents are required, such as:
- Full credit report & score analysis
- Statements for all outstanding debts (loans, credit cards, car financing)
- Co-borrower financials if applying with a partner
Anti-Money Laundering (AML) Compliance & Down Payment Scrutiny
The rise in foreign investment and money laundering scandals in Canada’s real estate market has triggered even stricter documentation rules.
The Canadian government has introduced stricter anti-money laundering (AML) laws, requiring banks and lenders to track all large financial transactions.
How This Affects Mortgage Documentation:
- Buyers must prove the source of their down payment to ensure it is legally acquired.
- Lenders now require 90-day bank statements to verify savings history.
- Gifted down payments must be documented with a signed letter confirming the funds are not a loan.
- Lenders now require non-residents and foreign buyers to provide:
- Larger down payments (typically 35% or more)
- Proof of income & tax filings in their home country
- Verification of legitimate funds (anti-money laundering compliance)
Without these extra steps, international buyers could use Canadian real estate to launder money, which has been a significant concern for financial regulators.
Why This Matters
- Prevents money laundering through real estate.
- Ensures buyers are not secretly borrowing funds to appear more financially stable.
Stricter Appraisal & Property Verification Rules
Twenty years ago, lenders often approved mortgages without requiring independent property appraisals. Today, this is no longer the case:
- Market volatility has increased the risk of properties being overvalued.
- FSBO (For Sale By Owner) transactions and private deals require extra scrutiny.
- Lenders need appraisals to ensure the home’s value aligns with the loan amount.
What Lenders Require Today:
- Independent property appraisals (ordered by the lender)
- Inspection reports for high-ratio mortgages
- Condo financial statements (if applicable)
The Role of Technology & Data Transparency
Advancements in digital banking and financial data sharing have given lenders instant access to more borrower information than ever before.
Then vs. Now:
- 2000s: Lenders relied on physical documents and employer letters.
- Today: Lenders use automated data retrieval from credit bureaus, tax agencies, and banking institutions.
Impacts on Documentation
Lenders now require direct access to bank statements & tax documents to cross-check income claims.
More digital tools allow lenders to detect inconsistencies between reported earnings and actual financial activity.
Summary
The mortgage approval process has evolved due to global financial crises, increased fraud risks, rising home prices, and employment changes. While it may seem frustrating to provide extensive documentation, these requirements exist to protect both borrowers and lenders from financial instability.
Today’s mortgage process is about more than just proving income—it’s about demonstrating long-term financial resilience. Ensuring accurate, verifiable documentation is essential for securing a mortgage in this new era of heightened lender scrutiny.