
… Why Service Matters More Than You Think When Getting a Mortgage
When you buy a home, you’re not just signing up for a set of keys and a welcome mat—you’re taking on the biggest financial commitment you’ll likely make in your entire life. The mortgage you choose will shape your finances for decades. That’s why the level of knowledge, care, and service you get should match the size of that commitment.
But here’s the kicker—too many people treat their mortgage like they’re buying a pair of sneakers: quick decision, find the cheapest deal, and hope it fits. In the mortgage world, that approach can cost you thousands… sometimes tens of thousands.
Let’s break this down so you can see why the service behind your mortgage matters just as much—if not more—than the rate in front of you.
Topics I’ll Cover
Mortgages: Bigger Than Just the Rate
You Don’t Know What You Don’t Know
The “Discount” Trap: You Get What You Pay For
The Bona Fide Sale Clause Trap
Why a Licensed Mortgage Professional Makes All the Difference
Putting Service Into Practice: For Realtors and Clients
Story: The Mortgage That Almost Cost a Family $40K
Mortgages: Bigger Than Just the Rate
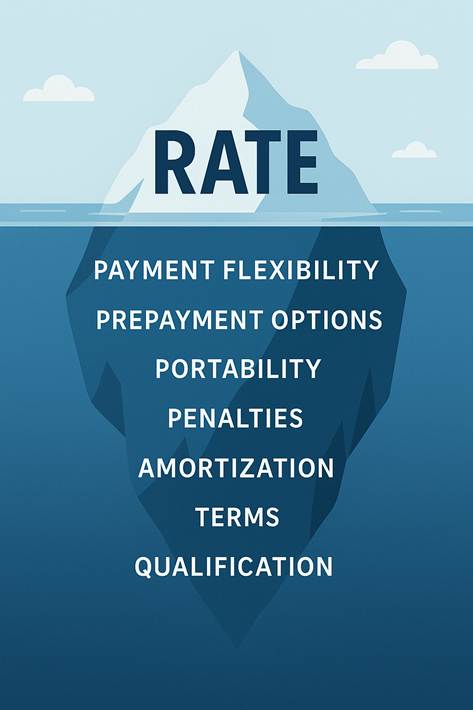
Everyone loves to talk about the rate. It’s shiny, it’s easy to compare, and it makes for a great headline in an ad. But a mortgage is far more than a rate. Payment flexibility, prepayment options, portability, penalties—these details can make or break your future financial flexibility. If you’ve only looked at the rate, you’ve missed the fine print that could save or cost you big time when life changes.
You Don’t Know What You Don’t Know
Here’s the thing — clients can’t ask questions about things they don’t know exist. Rate is the easiest thing to focus on because it’s simple to understand, but it’s also the shallowest part of the mortgage decision. What really matters is what’s happening in the market right now, what the trends suggest, and how that intersects with your personal situation — which is different from anyone else’s. How do you realistically assess your own risk tolerance? What happens if your income changes, rates rise, or you need to refinance early? These aren’t “one-size-fits-all” questions, and the answers depend on your life, your goals, and your long-term plans. Only a licensed mortgage agent will ask the questions you didn’t even know to ask, share opportunities, risks, and strategies and put you on the path to financial success — and that’s where the real value lies. Ever wonder why some people get ahead and others don’t? It’s because they have a professional like me in their corner guiding them, helping them, showing them how.
The “Discount” Trap: You Get What You Pay For
Let’s talk about discount online mortgage brokers. Sure, they’ll plaster the internet with their flashy low rates, but here’s the thing—those rates often come with discount service. You gotta know, nothing is free in this world, and if something is cheap, it’s cheap for a reason.
Do they start by doing a deep dive to really understand you? Do they help you compare and contrast different lenders? Do they walk you through what penalties would look like if you had to break the mortgage early? What’s the long term strategy they have created for you? Do they explain the difference between an open mortgage, a variable rate, and a hybrid mortgage in plain English? Do they follow up with you and provide you with opportunities to save you money long after your mortgage documents have been signed? No, they are wham bam thank you M’am. And when you buy “discount” service, you risk making a decision based solely on short term price, without understanding the long-term cost.
Banks: The Shoe Sales Problem
Here’s a hard truth—no one who sells mortgages at a bank is licensed to sell mortgages. There is no specific industry education required whatsoever. They are purely commissioned salespeople. Their job is not to compare the whole market or find you the best mortgage—it’s to sell you their bank’s mortgage, period.
And here’s the reality: even if they know another lender has a better product or a better rate for you, they will never tell you. Why? Because it’s not their job to help you shop around—it’s their job to close the sale for their employer. It’s no different than walking into a car dealership and expecting the salesperson to tell you the better deal is across the street. It’s just not going to happen.
The Bona Fide Sale Clause Trap
This is one of the nastiest “gotchas” hiding in mortgage fine print, and almost no one tells you about it until it’s too late. A bona fide sale clause says that you can only break your mortgage early if you sell the property to an unrelated third party.
Translation? If you want to refinance to get a better rate, consolidate debt, or access equity for renovations—you can’t. You’re locked in.
Where will you find it? Usually buried deep in the mortgage commitment or the standard charge terms—documents most people never read in full. Why is it there? Because lenders use it to protect their discount, low-rate offers by stopping you from jumping ship early.
Here’s the problem: the salesperson or discount broker offering that “super-low special” rate often doesn’t mention this clause. They are supposed to, but, well, you know… Why? Because telling you could scare you off, and their goal is to close the deal, fast. Get them on the phone, does anyone talk faster? They make their money on volume. The result? You think you’ve scored a win with the lowest rate, only to find out years later that you’re trapped unless you sell your home—at which point you might have to pay enormous penalties or forfeit great financial opportunities.
Why a Licensed Mortgage Agent Makes All the Difference
This is where working with someone like me—a licensed mortgage agent—becomes a game-changer. I don’t just have access to one lender; I have access to prime lenders, alternative lenders, and even private lenders. That means we can craft a strategy around your goals, whether it’s paying off your mortgage faster, investing in real estate, or setting yourself up to retire comfortably. I’m with you every step of the way.
Putting Service Into Practice: For Realtors and Clients
If you’re a realtor, this is your opportunity to bring extra value to your clients. Pairing them with a mortgage professional who can look beyond the rate means they’re more likely to close smoothly, avoid last-minute financing disasters, and remain loyal to you for future transactions.
If you’re a client, here’s how to put this into action:
- Ask your mortgage professional if there are any bona fide sale clauses in the mortgage they’re recommending.
- Request that they walk you through the penalties for breaking early—not just the rate.
- Ensure they present at least three lender options so you can make a fully informed choice.
Story: The Mortgage That Cost a Family $40K
A family come to me in a panic. They’d gone with a bank because the rate looked great on paper (one of those ‘special offer’ or ‘low rate’ products). Fast forward two years—they needed to relocate for work. When they called their bank to break the mortgage, they were hit with a $40,000 penalty.
And here’s the kicker: even if they’d wanted to refinance instead of sell, they couldn’t have—because their contract had a bona fide sale clause. That single hidden clause eliminated almost every financial option they had.
If they’d worked with a licensed mortgage agent like myself from the start, I could have set them up with a mortgage that had a much lower penalty or more flexible terms. Instead, they got sold a product that wasn’t good for them. These are smart people, both have masters degrees, but they are like most other people; they are not mortgage experts. You don’t know what you don’t know, and you can’t ask questions about things you don’t know about. That’s the difference service makes—it’s not just about today, it’s about protecting you tomorrow.
Allen’s Final Thoughts
When you’re making the biggest financial decision of your life, you deserve more than a cookie-cutter mortgage and a smile from someone who’s not accountable for their advice. You deserve a licensed professional who will dig deep, ask the right questions, compare across the market, and craft a mortgage strategy that works for you now and in the future.
Service matters because mortgages aren’t one-size-fits-all. They’re personal, they’re strategic, and they require foresight. Cheap service can cost you dearly. Quality service can save you time, money, and stress. And sometimes, it can protect you from being trapped by clauses you didn’t even know existed—like the bona fide sale clause.
How I Can Help You
As your mortgage agent, here’s what I can do for you:
- Access and compare options from prime, alternative, and private lenders.
- Identify and explain hidden clauses—like bona fide sale restrictions—before you sign.
- Build a long-term mortgage strategy tailored to your goals.
- Protect you from costly surprises like massive prepayment penalties.
- Collaborate with your realtor to make your home buying (or selling) process smooth and stress-free.
Whether you’re buying your first home, refinancing, or investing, I’m here to ensure you get not just the best mortgage—but the right mortgage. Let’s make a plan that works for you today and sets you up for success tomorrow.











