
Mortgage Terms
Get a Better Understanding of Mortgages!





Understanding Subordination Agreements
A subordination agreement is a legal document that modifies the lien priority of two or more mortgages on a property. In the context of first and second position mortgages, this agreement allows a lender with a lower-ranking mortgage (such as a second mortgage or a...
Mortgage Term: Balloon Payment
A large, lump-sum payment due at the end of a mortgage’s term. You make a balloon payment when you pay out your mortgage, renew, refinance, or transfer your mortgage to another lender for better rates and terms. A balloon payment is often part of loans that have lower...
Mortgage Term: Blend and Extend
Discover blend and extend, and see what it is such an important refinancing option that could save you tens of thousands of dollars.
Understanding Market Rent
Understanding Market Rent: More homebuyers today rely on rental income to qualify for mortgages. If you’re one of them, you’ll often need a market rent report or rent letter to “prove” that income to the lender.
Understanding Exit Strategies
Understanding Exit Strategies. How getting out of a Private mortgage is more important as getting in.
When a Second Mortgage Makes Sense
Second Mortgage: When it Makes Sense and when and why it can be the better move.
Mortgage Term: Closed-End Lease
Discover what a closed-end lease is and the options and benefits.
How I Structure Second Mortgages
Second Mortgage Structure: How I treat your second mortgage as a full mocrtgage file with structure, risk analysis and a clear strategy.
The 5 C’s of Credit and Your Mortgage
Unlock the secrets to mortgage approval in Canada by mastering the 5 C’s of Credit, crucial for securing your dream home.
Mortgage Term: Beta
In the context of finance, beta is a technical indicator that measures the volatility or systemic risk of an investment relative to the overall market. Beta indicates how much an investment's price is expected to move in relation to a market benchmark, such as the...
Paystub and Your Mortgage
Learn why pay stubs are so crucial when applying for a mortgage. Discover how they are used and how they support your application
Mortgage Term: Informal Trust
Discover the implications of an informal trust account. their key features, and their relationship to mortgages in Canada.
Understanding Bank Posted Rates
Understanding Bank Posted Rates. You can’t calculate your bank’s mortgage penalty without knowing your bank’s posted rates.
PMB Professional Mortgage Brokers
PMB Professional Mortgage Brokers: The Small Eastern Ontario Mortgage Investment Entity with the big heart.
Mortgage Term: Letter of Credit
Discover how a Letter of Credit issued by a bank or financial institution guarantees payment and secures a purchase.
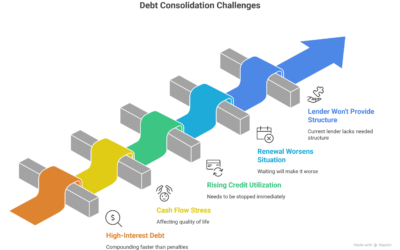
Switching Lenders Mid-Term to Consolidate Debt
Switching Lenders Mid-Term to Consolidate Debt: Switching lenders mid-term to consolidate debt is one of the most misunderstood strategies in Canadian mortgage planning. In many cases, switching lenders mid-term isn’t the flashy option—it’s the necessary one.
Using Blend and Extend to Consolidate Debt
Using Blend and Extend to Consolidate Debt: For the right borrower, a blend and extend can be a practical, lower-friction way to restructure debt, access equity, and improve cash flow without fully blowing up your existing mortgage. It’s not a magic fix, and it’s not available in every situation
Climbing the Mortgage Ladder
Mortgage Ladder: Life doesn’t always unfold in neat, predictable steps. Sometimes you get bruised credit after a divorce, sometimes your business income doesn’t show well on paper, and sometimes the bank just flat-out says “no.” That’s when the mortgage ladder comes into play: starting where you are, even if that’s at the bottom rung, and climbing steadily toward prime lending.
Exceptions that Bend the Rules
Behind every approval—or decline—is a framework called underwriting policy. These policies give lenders structure and consistency. But they also leave room for exceptions, where a skilled mortgage professional can present a file in a way that helps a lender say yes instead of no.

Second Mortgages Explained
… Position, Priority, and the Power—and Peril—of Layered Debt Second mortgages sit in one of the most misunderstood corners of Canadian real estate finance. They’re powerful, flexible, and sometimes exactly the right tool. They’re also easy to misuse, easy to...

Understanding Addbacks
Understanding Addbacks: In Canadian mortgage lending, addbacks are one of the most important (and most misunderstood) tools for turning taxable income into true cash-flow income—without pretending, stretching, or “making numbers up.”

Waiving the Condition of Financing
Waiving Condition of Financing: In practice, it’s one of the most stressful pressure points in the entire transaction, especially when markets are competitive and timelines are tight.
Featured Publications
Articles
- Extended Amortizations and Hypothetical Calculations
Office of the Superintendent of Financial Institutions (OSFI) - Minimum Qualifying Rate for Uninsured Mortgages
Office of the Superintendent of Financial Institutions (OSFI) - Residential Mortgage Underwriting Practices and Procedures
Office of the Superintendent of Financial Institutions (OSFI) - Guideline on Existing Consumer Mortgage Loans in Exceptional Circumstances Financial Consumer Agency of Canada
Book: “The Program”
- Part 1 – Building Your Down Payment
- Part 2 – Mortgage Payoff Strategies
- Part 3 – Building Wealth Through Real Estate