
… The 5 Costly Mistakes That Get Strong Borrowers Declined
Commission income is one of the most misunderstood types of income in Canadian mortgage underwriting. If you work with realtors, financial advisors, insurance professionals, or sales executives, you already know the pattern. The borrower is successful, earns excellent income, and has strong credit—yet the mortgage gets declined.
More often than not, the problem isn’t the borrower.
The problem is how the file was submitted.
Prime lenders are perfectly comfortable lending to commission-based professionals. In fact, many of their best clients fall into this category. But underwriting commission income requires precision. If a file is structured incorrectly, lenders may calculate the income incorrectly—or reject it altogether.
And when that happens, strong borrowers who should qualify for prime financing sometimes get pushed into alternative lending unnecessarily.
Understanding the common mistakes brokers make when submitting commission income files can make the difference between a smooth approval and a frustrating decline.
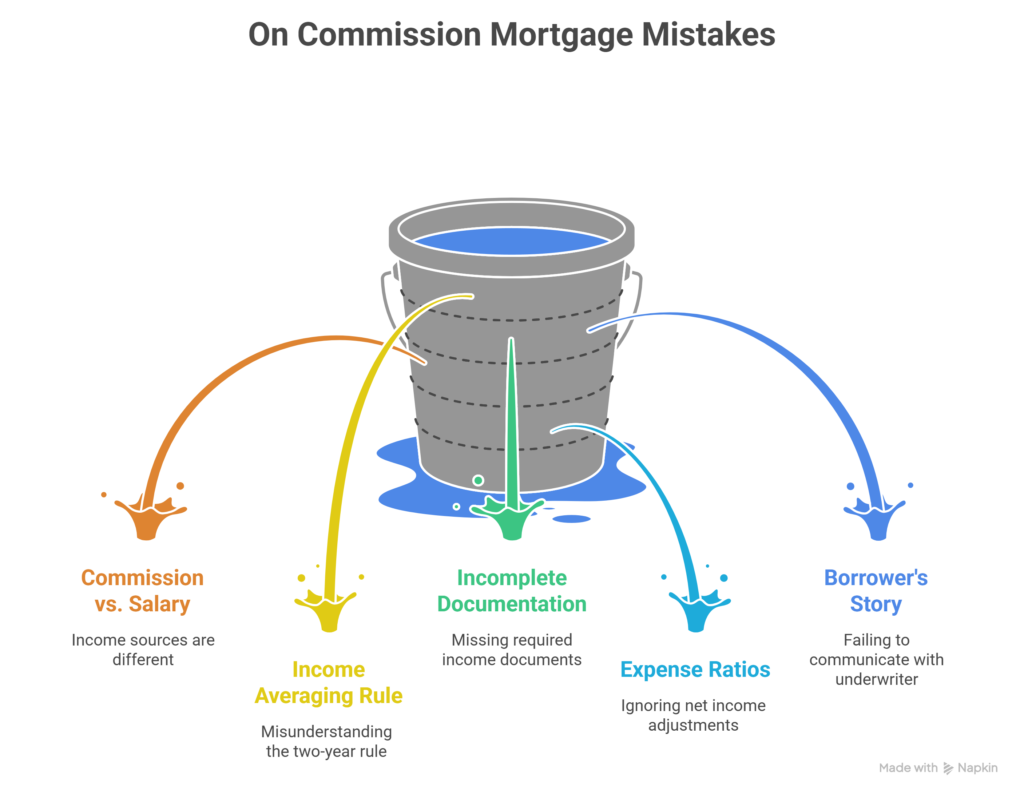
Topics I’ll Cover in This Article
Commission Income Isn’t the Same as Salary
Misunderstanding the Two-Year Income Averaging Rule
Submitting Incomplete Income Documentation
Ignoring Expense Ratios and Net Income Adjustments
Failing to Tell the Borrower’s Story to the Underwriter
When Going to the Bank Isn’t the Best Idea
Commission Income Isn’t the Same as Salary
One of the most common mistakes brokers make is treating commission income as if it were regular salaried income.
Prime lenders view commission income differently because it tends to fluctuate. Instead of simply verifying a salary figure, underwriters must assess income stability over time.
Typically, lenders want to see:
- A two-year history of commission income
- Consistent or increasing earnings
- Evidence that the income is sustainable
But here’s where files often go sideways. A broker submits a letter of employment stating a strong annual income figure, assuming that will be sufficient.
It usually isn’t.
Underwriters rely heavily on historical earnings, not projections.
If the income documentation isn’t aligned with underwriting guidelines, the lender may reduce the qualifying income—or decline the file entirely.
Misunderstanding the Two-Year Income Averaging Rule
Most prime lenders average commission income over two years using tax returns.
That seems simple, but mistakes happen all the time.
For example, a borrower might have earned:
- $80,000 two years ago
- $140,000 last year
Some brokers mistakenly submit the file based on the most recent income.
But underwriters will typically average the two years, resulting in a qualifying income of $110,000.
However, exceptions can sometimes apply.
If income has clearly increased due to career progression, a skilled mortgage professional can often make a case for using the most recent year or a modified average.
This is where thoughtful file presentation becomes critical.
Submitting Incomplete Income Documentation
Another frequent issue is incomplete documentation.
Prime lenders usually require several pieces of verification for commission income:
- Two years of T1 General tax returns
- Two years of Notices of Assessment
- A letter of employment
- Recent pay stubs or commission statements
If even one piece of documentation is missing, underwriters may be forced to make conservative assumptions about income.
That can dramatically reduce the borrower’s qualifying amount.
Sometimes it even triggers an automated decline.
A well-prepared file anticipates these requirements and provides a complete documentation package upfront.
Ignoring Expense Ratios and Net Income Adjustments
Commission earners often claim significant expenses on their tax returns.
This is common among professionals like:
- Realtors
- Insurance advisors
- mortgage professionals
- financial planners
While those deductions reduce taxable income, they can also reduce qualifying income for mortgage purposes.
A broker who simply looks at gross commission numbers without reviewing the net taxable income may dramatically overestimate the borrower’s qualifying capacity.
However, experienced mortgage agents sometimes identify legitimate ways to add back certain expenses when lenders permit it.
Examples may include:
- vehicle allowances
- cell phone expenses
- home office costs
When these adjustments are documented properly, they can sometimes improve the borrower’s qualifying income significantly.
Failing to Tell the Borrower’s Story to the Underwriter
Mortgage underwriting is about numbers—but it’s also about context.
One of the biggest mistakes brokers make is submitting a file without explaining the borrower’s situation.
Underwriters review dozens of files every day. If a commission income file looks inconsistent on paper, the safest decision may be to decline it.
But when the file includes a clear explanation, the underwriter gains confidence.
For example:
- A borrower recently moved to a higher-performing brokerage
- A financial advisor acquired a new client book
- A sales professional moved into a more lucrative territory
These types of career developments can explain income growth and stability.
Without that narrative, the file may appear riskier than it actually is.
When Going to the Bank Lending Isn’t the Best Idea
It’s also important to remember that if a file doesn’t quite fit within prime lending guidelines, that doesn’t mean the financing journey stops there. Canada’s mortgage market includes a wide spectrum of lenders, and alternative lending can sometimes be the more practical solution for commission-based professionals, especially those who structure their income strategically for tax efficiency.
Many self-employed and commission earners legitimately reduce their taxable income through business deductions—vehicle expenses, marketing costs, office space, technology, and other operating expenses. From a tax planning perspective, that’s smart. The trade-off, however, is that lower declared income can make qualifying with prime lenders more difficult.
In these cases, alternative lenders often assess the borrower’s financial profile more holistically, sometimes using stated income programs or alternative income verification methods. While the interest rate may be slightly higher than prime financing, the overall financial outcome can still be very favourable. After all, if reducing taxable income saves a borrower tens of thousands of dollars in taxes over several years, paying a slightly higher mortgage rate may still leave them significantly ahead financially.
For many entrepreneurs and commission professionals, alternative lending isn’t a fallback—it’s simply a different tool that aligns better with how their income is structured. And with the right strategy, many borrowers transition back to prime lending later once their financial documentation aligns with conventional underwriting requirements.
A Story from the Field
A few years ago, a realtor contacted me about a client who had just been declined by a major bank.
The borrower was a top-performing real estate agent.
Their credit was excellent.
Their income was strong.
So what went wrong?
The original application had been submitted using the borrower’s gross commissions, without properly analyzing the tax returns.
When the underwriter reviewed the file, the net income appeared much lower due to business deductions.
The bank declined the deal.
But after reviewing the file carefully, I realized something important.
Many of those deductions were standard operating expenses, and several could be legitimately addressed through lender policies.
By restructuring the file and presenting the borrower’s income clearly, we secured a prime approval through a different lender.
Same borrower.
Same income.
Completely different outcome.
That’s the difference proper underwriting strategy can make.
How Realtors Can Use This Knowledge
Realtors often work with commission-based professionals just like themselves.
Understanding how lenders evaluate commission income can help you guide clients more effectively.
For example, you can encourage clients to:
- maintain organized financial records
- work with mortgage agents experienced in complex income
- plan financing strategies well before purchasing
When commission earners prepare in advance, their mortgage approvals become much smoother.
How Financial Professionals Can Apply These Insights
Financial planners and accountants can also help clients position themselves for mortgage success.
Simple steps can make a big difference, such as:
- helping clients understand how deductions affect borrowing power
- timing major purchases strategically
- coordinating with mortgage professionals before major financial decisions
A collaborative approach often produces the best outcomes.
How Borrowers Can Prepare
If you earn commission income, preparation is your biggest advantage.
Start by keeping clean financial records and understanding how your income appears on tax returns.
You can also work with mortgage agents early to assess:
- your qualifying income
- your debt service ratios
- the lenders most likely to approve your file
That proactive approach often prevents unpleasant surprises later.
Allen’s Final Thoughts
Commission income borrowers are some of the strongest clients in the mortgage market. They’re entrepreneurial, motivated, and often financially successful.
Yet many of them run into unnecessary mortgage roadblocks simply because their files are not structured properly.
Understanding how lenders evaluate commission income—and avoiding the common mistakes brokers sometimes make—can dramatically improve approval outcomes.
A thoughtful mortgage strategy looks beyond the numbers and considers the full financial story.
That’s where experience and underwriting insight make a real difference.
Whether you’re a realtor helping a client purchase a home, a financial professional guiding long-term planning, or a commission-based professional preparing for a mortgage, having the right strategy in place can open doors.
My role as a mortgage agent is to help structure complex income files, present them effectively to lenders, and advocate for the best possible financing options available.
If your income doesn’t fit neatly into a traditional box, don’t worry—there’s often more flexibility in the system than most people realize.
And I’m here to help you navigate it.











