In Canada, the mortgage application process is highly regulated, requiring strict compliance with financial and legal documentation standards. For borrowers whose mortgage application documents are in a language other than English or French, lenders demand certified translations to ensure clarity, consistency, and compliance with lending policies.
The challenge? Not all translations are created equal. Poorly translated documents can delay approvals, trigger compliance red flags, or even lead to a rejected mortgage application. Whether it’s a bank statement, income verification, or property sale agreement, getting it professionally translated is not just an administrative task—it’s a critical step toward homeownership.
Why Mortgage Lenders Require Translated Documents
Documents That May Need Translation
Who Can Translate Mortgage Documents?
Does a translation need to be notarized?
Translation Costs and Timelines
Why Mortgage Lenders Require Translated Documents
Lenders must adhere to strict compliance rules when assessing mortgage applications. If a borrower provides documents in a foreign language, the lender requires a certified English or French translation to:
- Ensure accuracy in assessing financial history.
- Verify employment, tax records, and proof of down payment.
- Prevent fraud or misrepresentation of financial standing.
- Ensure underwriting compliance with Canadian financial laws.
Since lenders cannot process documents in unfamiliar languages, translations must be official, precise, and free of misinterpretations. Any inconsistency between the original and translated versions can jeopardize mortgage approval.
Mortgage lenders enforce strict due diligence policies to prevent fraud, money laundering, and financial misrepresentation. One aspect of this due diligence is ensuring that all documentation is:
- Legally accurate and verifiable.
- Consistent with Canadian mortgage underwriting standards.
- Translated by a certified professional, ensuring no misinterpretations.
By requiring official translations, lenders can confidently assess a borrower’s financial standing, income stability, and creditworthiness—regardless of where their original documents were issued.
Documents That May Need Translation
Not all mortgage applicants will need translated documents, but borrowers with foreign financial records typically must provide certified translations of the following:
Bank Statements & Proof of Down Payment
- Foreign bank account statements proving available funds.
- Wire transfer receipts for funds moved to Canada.
Employment & Income Verification
- Pay stubs and salary confirmation letters.
- Foreign tax returns or income statements.
Property Sale Agreements (If Using Sale Proceeds as a Down Payment)
- Real estate contracts proving the sale of an overseas property.
- Land registry records and legal ownership transfers.
Gift Letters & Inheritance Documents
- If down payment funds are a gift from family, the gift letter must be translated.
- Wills and estate documents confirming inheritance funds.
Government-Issued Identification & Legal Documents
- Passports, visas, residency documents, and marriage certificates (if applicable to the mortgage).
Lenders expect complete and professional translations, with no missing pages or altered information.
Who Can Translate Mortgage Documents?
Mortgage lenders require translations to be performed by a certified professional. This typically means:
- A translator accredited by a recognized association, such as:
- A professional with legal and financial translation expertise.
- A translation service that provides an official certificate of accuracy.
Lenders do not accept self-translations, translations by family members, or Google Translate outputs—even if the translation appears accurate.
Does a Translation Need to Be Notarized?
Notarization is the process of certifying the authenticity of a document, signature, or translation by a notary public—a legally authorized official. Notarization ensures that documents are legitimate, trustworthy, and legally recognized by courts, financial institutions, and government bodies.
In the context of mortgage applications, notarization may be required for translated documents, financial records, or legal agreements to confirm their validity.
Notarization is not always mandatory, but in cases where documents are:
- Legal contracts (such as real estate purchase agreements).
- Wills or inheritance documents.
- Government-issued identification.
A notarized translation ensures the authenticity and accuracy of the document.
Translation Costs and Timelines
Translation costs depend on language complexity, document type, and urgency. Here’s a general pricing guide:
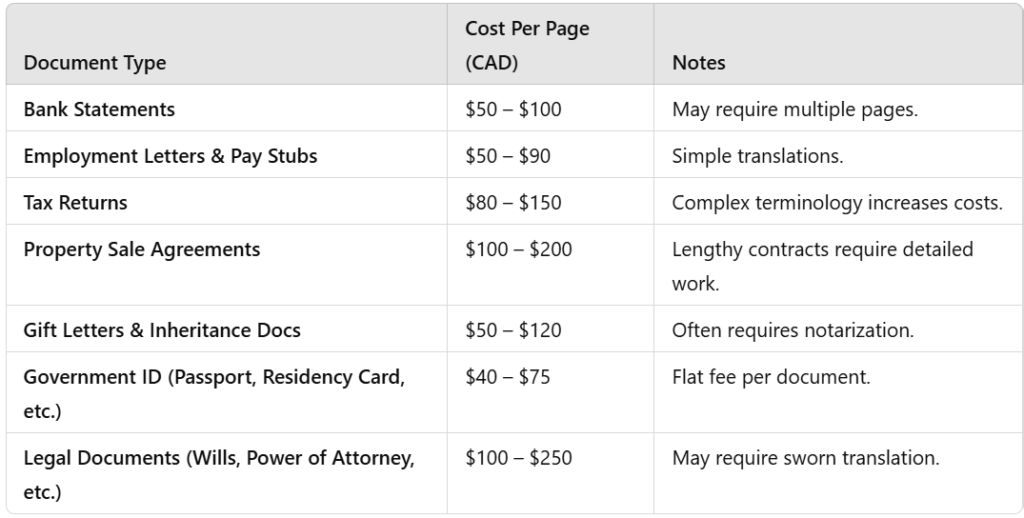
Rush services (24–48 hours) cost 25%–50% more than standard turnaround (3–5 business days).
Summary
Getting mortgage documents translated is not just a formality—it’s a lender requirement that can impact mortgage approval timelines. Whether you’re a newcomer to Canada, a foreign investor, or someone with overseas assets, ensuring your documents are accurate, certified, and lender-approved is crucial.
By working with certified professionals, budgeting for translation costs, and submitting documents well in advance, borrowers can avoid unnecessary delays, rejections, or compliance issues—ensuring a smooth path to homeownership in Canada.