
… Stop Feeding the Bank by using Allen Ehlert’s Ultimate Canadian Mortgage-Free Accelerator Calculator
Let’s be honest—owning a home is amazing, but sometimes your mortgage feels less like an investment and more like a leash. Especially in the early years, when your balance is high, it can feel like every payment is gobbled up by interest while your principal barely budges. For many Canadians, it feels like trading rent for mortgage—different landlord, same problem.
Here’s the truth: the secret to building wealth isn’t just owning a home—it’s owning it faster. The trick is to shave years (and thousands of dollars) off your mortgage by paying down the principal as quickly as possible. But how do you know which levers to pull? Do you increase payments, make lump sums, switch frequency—or all of the above?
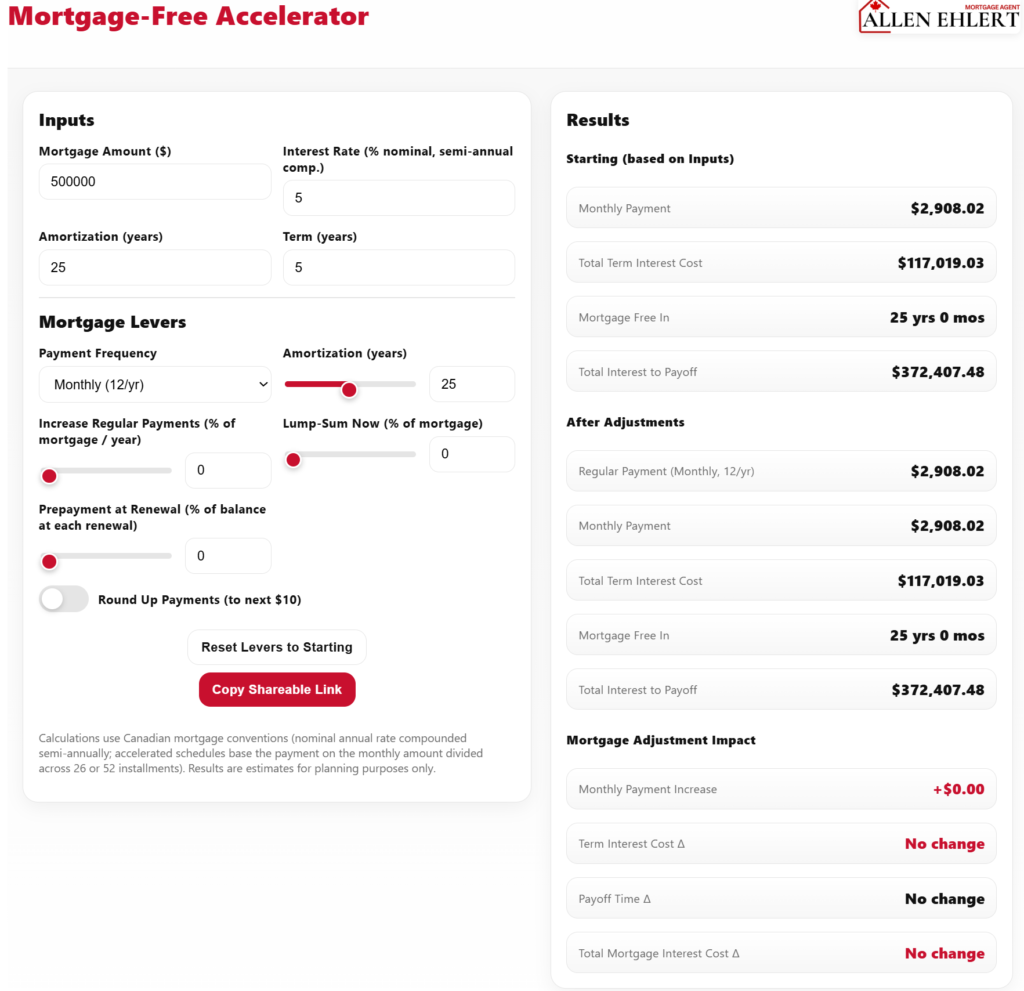
That’s where Allen Ehlert’s Ultimate Canadian Mortgage-Free Accelerator Calculator comes in. This tool lets you see the impact of even the tiniest adjustments to your mortgage so you can make informed choices that accelerate your path to financial freedom.
Here’s what I’ll dig into today:
Why Accelerating Your Mortgage Matters
How the Mortgage-Free Accelerator Works
Real-World Examples for Realtors and Clients
A Story That Brings It All Home
Why Accelerating Your Mortgage Matters
Banks make billions off mortgage interest. In the first five to ten years of a mortgage, most of your payment goes straight into their pockets, not toward building your equity. If you just pay the bare minimum, you’re on their schedule—not yours.
By accelerating your mortgage, you flip the script. You redirect money from interest toward principal, shorten your amortization, and build wealth faster. Every small tweak compounds into big savings.
Think of it like fitness—skipping dessert once in a while doesn’t seem like much, but over time it reshapes your health. The same goes for your mortgage.
How the Mortgage-Free Accelerator Works
Using the calculator is simple and eye-opening. Here’s how:
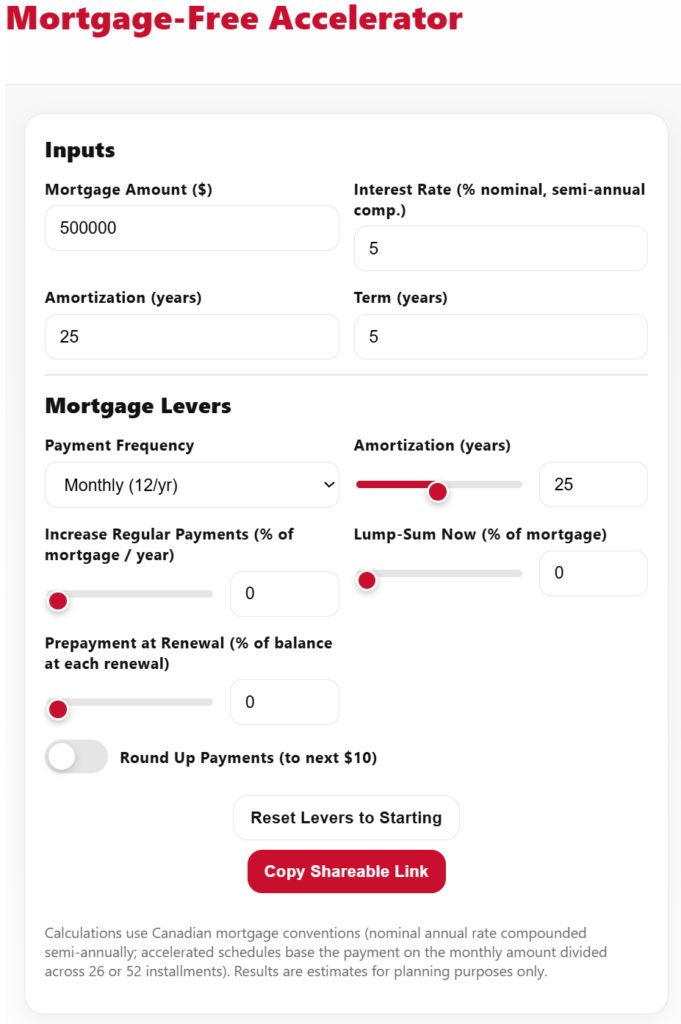
- Enter your mortgage details—amount, rate, term, and amortization.
- Play with the variables: try bi-weekly instead of monthly payments, increase your regular payment slightly, or add in lump sums.
- Watch the results—the calculator shows you instantly how much interest you’ll save and how many years you’ll chop off your mortgage.
It’s not just about theory—you see the real dollars and time you stand to save. And that’s powerful motivation.
Real-World Examples for Realtors and Clients
For clients, this tool is about empowerment. Let’s say you’ve got a $500,000 mortgage at 5%. By switching to accelerated bi-weekly payments, you could cut years off your mortgage and save tens of thousands in interest. Add an extra $100 a month, and you’ll shave off even more.
For realtors, the calculator is a value-add. Buyers often feel discouraged by the long amortization they’ve signed up for. Show them how even small tweaks can fast-track their freedom, and you become not just their agent, but part of their financial success team.
A Story That Brings It All Home
Meet Kevin and Sofia. They bought their first home in Ajax with a $450,000 mortgage. At first, they stuck to the standard monthly payments. But when they ran their numbers through Allen’s Mortgage-Free Accelerator, they realized the bank was set to make nearly $350,000 in interest over the life of their mortgage.
Shocked, they decided to act. They switched to bi-weekly payments and added an extra $75 each cycle. Suddenly, their payoff timeline shrank by seven years—and they saved over $80,000 in interest.
Instead of being chained to debt into their late 50s, they saw a path to being mortgage-free by their early 40s. That shift in perspective changed everything for them.
Allen’s Final Thoughts
Mortgages are designed to make banks rich—not you. But with the right strategy, you can turn the tables. The Ultimate Canadian Mortgage-Free Accelerator Calculator gives you a clear, no-nonsense way to see exactly how small adjustments can lead to massive savings.
Every extra dollar toward your principal isn’t just a payment—it’s a step closer to true financial freedom. And when you’re mortgage-free years ahead of schedule, the wealth you’ve built isn’t just numbers on paper—it’s peace of mind, opportunity, and security.
How I Can Support You
The calculator gives you the raw numbers, but as your mortgage agent, I can help you create a real plan to put those numbers into action. Here’s what I can do for you:
- Review your mortgage terms and show you what prepayment privileges you can take advantage of.
- Build a strategy to maximize your savings without straining your budget.
- Negotiate the right mortgage product that allows the flexibility you’ll need to accelerate.
- Keep you updated with renewal strategies to ensure you stay ahead of the bank’s game.
At the end of the day, I’m here to help you own your home faster and keep more money in your pocket. Because wealth isn’t built by making banks rich—it’s built by taking control of your financial future, one smart move at a time.











