In Canada, there are about 10 different kinds of lenders, offering prime, alternative, and subprime mortgages that are insured, uninsured, and insurable while also being conventional or collateral. There are literally thousands of different mortgage products on the market, coming to the market and disappearing from the market all the time. So which do you choose?
Mortgages are in some ways a lot like pharmaceuticals. A drug that is good for one person is bad for another. So too is it with mortgages and financial products in general. This is why it is important to work with a license professional to discover the mortgage that is best for you.
For Canadian homeowners looking for a mortgage that offers flexibility, access to home equity, and financial security, BMO’s Homeowner ReadiLine is a strong contender. This readvanceable mortgage allows borrowers to combine a traditional mortgage with a home equity line of credit (HELOC), providing a versatile financing option for those who want ongoing access to their home’s equity.
Unlike a standard mortgage, which requires refinancing to access additional equity, the Homeowner ReadiLine automatically increases the available HELOC credit as mortgage payments are made. This makes it an attractive option for homeowners who want a financial safety net, investment opportunities, or cash flow management without the hassle of reapplying for credit.
While the Homeowner ReadiLine offers significant benefits, it may not be the best fit for every borrower. This guide examines its features, who benefits the most, and who might be better suited to a different mortgage product.
Understanding the BMO Homeowner ReadiLine
Who Benefits Most from the BMO Homeowner ReadiLine?
Who Should Avoid the BMO Homeowner ReadiLine?
Example Scenario: How a Homeowner Uses the BMO Homeowner ReadiLine
Is the BMO Homeowner ReadiLine Right for You?
Understanding the BMO Homeowner ReadiLine
The BMO Homeowner ReadiLine is a hybrid mortgage product that allows homeowners to manage their mortgage debt and home equity access more effectively. It consists of two primary components:
- The Mortgage Portion – Borrowers can choose between fixed-rate and variable-rate options for structured mortgage payments.
- The Home Equity Line of Credit (HELOC) Portion – A revolving credit line that grows as mortgage principal payments are made, allowing homeowners to borrow against their home equity without refinancing.
A major advantage of the Homeowner ReadiLine is that the HELOC portion can be accessed at any time, and borrowers can choose to make interest-only payments on the HELOC to keep monthly expenses low.
Who Benefits Most from the BMO Homeowner ReadiLine?
This mortgage product is best suited for homeowners who want ongoing access to their home equity while maintaining a structured mortgage. Several groups may find this mortgage solution particularly useful.
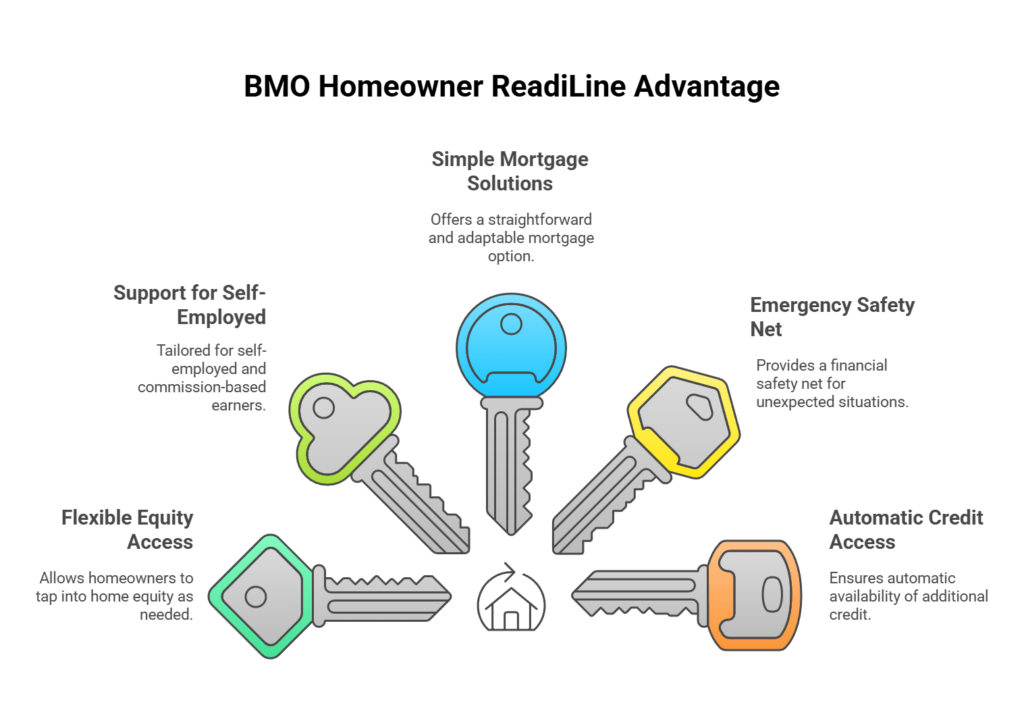
- Homeowners Who Want Flexible Access to Home Equity
- Self-Employed Individuals and Commission-Based Earners
- Borrowers Looking for a Simple and Flexible Mortgage
- Homeowners Who Want a Safety Net for Emergencies
- Borrowers Who Want Automatic Access to Additional Credit
Homeowners Who Want Flexible Access to Home Equity
The Homeowner ReadiLine is ideal for borrowers who anticipate needing access to funds for large expenses, such as home renovations, tuition fees, debt consolidation, or investments. The HELOC allows homeowners to borrow as needed without requiring additional loan applications or refinancing.
Self-Employed Individuals and Commission-Based Earners
For those with fluctuating income, such as entrepreneurs, freelancers, and real estate agents, having a HELOC portion as part of their mortgage provides an important financial cushion. The ability to make interest-only payments on the HELOC ensures that these borrowers can maintain cash flow stability while still accessing credit when necessary.
Borrowers Looking for a Simple and Flexible Mortgage
The Homeowner ReadiLine offers a straightforward mortgage structure without multiple segmented loan components. Unlike Scotiabank STEP, which allows borrowers to split their mortgage into multiple parts, the Homeowner ReadiLine keeps things simple, with one mortgage portion and one HELOC portion.
Homeowners Who Want a Safety Net for Emergencies
Life is unpredictable, and many homeowners prefer having quick access to cash in case of unexpected expenses. The HELOC feature provides peace of mind, allowing borrowers to handle emergencies without turning to high-interest credit cards or personal loans.
Borrowers Who Want Automatic Access to Additional Credit
One of the standout benefits of the Homeowner ReadiLine is that the HELOC automatically increases as the mortgage is paid down. This means that homeowners do not have to reapply for credit every time they want to access additional equity. Instead, their available credit grows alongside their mortgage repayment.
Who Should Avoid the BMO Homeowner ReadiLine?
Despite its advantages, the Homeowner ReadiLine is not the best fit for every borrower. Some homeowners may find that other mortgage products better suit their financial goals.
- First-Time Homebuyers with Less than 20% Down
- Homeowners Who Prefer a Fixed, Predictable Mortgage
- Real Estate Investors Needing Multiple Mortgage Segments
- Borrowers Looking for the Lowest Possible Interest Rate
First-Time Homebuyers with Less than 20% Down
To qualify for a HELOC, borrowers must have at least a 20% down payment or 20% home equity. First-time homebuyers with smaller down payments will need to look at traditional fixed or variable-rate mortgages instead.
Homeowners Who Prefer a Fixed, Predictable Mortgage
Some borrowers prefer a simple, fixed mortgage with no additional borrowing options. If a homeowner has no intention of using their home equity, then a standard fixed-rate mortgage may offer a lower interest rate and a more straightforward repayment structure.
Real Estate Investors Needing Multiple Mortgage Segments
Unlike Scotiabank STEP, which allows borrowers to have multiple mortgage segments, the Homeowner ReadiLine only provides one primary mortgage and one HELOC. Real estate investors who require separate mortgage portions for different properties may find Scotiabank STEP or TD FlexLine to be better alternatives.
Borrowers Looking for the Lowest Possible Interest Rate
Since the Homeowner ReadiLine includes a HELOC component, the mortgage portion may carry a slightly higher interest rate compared to non-readvanceable mortgages. Homeowners who do not plan to use the HELOC may prefer a traditional mortgage with a lower interest rate.
Example Scenario: How a Homeowner Uses the BMO Homeowner ReadiLine
Case Study: Mark and Lisa’s Smart Borrowing Strategy
Mark and Lisa are a married couple who own a $750,000 home with a 20% down payment ($150,000), leaving them with a $600,000 mortgage. They are both self-employed business owners, and their income fluctuates throughout the year. They want a mortgage that provides stability while also allowing access to funds when needed.
To meet their needs, they structure their BMO Homeowner ReadiLine as follows:
- $450,000 in a fixed-rate mortgage (5.19% for 5 years) for stable monthly payments.
- $150,000 available in a HELOC (Prime + 0.50%) to help cover business cash flow fluctuations and possible future investments.
This setup allows them to budget effectively with stable mortgage payments while still having access to additional funds when their income varies. If they need capital for business expansion, they can use the HELOC without applying for a new loan.
Is the BMO Homeowner ReadiLine Right for You?
The BMO Homeowner ReadiLine is an excellent mortgage option for homeowners who want a flexible HELOC combined with a structured mortgage. It is particularly beneficial for self-employed individuals, homeowners planning renovations, and those who need financial flexibility.
However, for borrowers who need multiple mortgage segments, the lowest possible interest rate, or a mortgage without a HELOC, other options like Scotiabank STEP or a standard fixed mortgage may be a better fit.
Would you like to determine if the Homeowner ReadiLine aligns with your financial goals? Speak with a mortgage professional today!
Give me a call if you would you like a personalized recommendation to determine if a BMO Homeowner ReadiLine mortgage is right for you.