… When Love Ends but the Mortgage Remains
When a couple separates and one spouse wants to remain in the home, one of the most powerful financing tools available in Canada is the Spousal Buyout Mortgage.
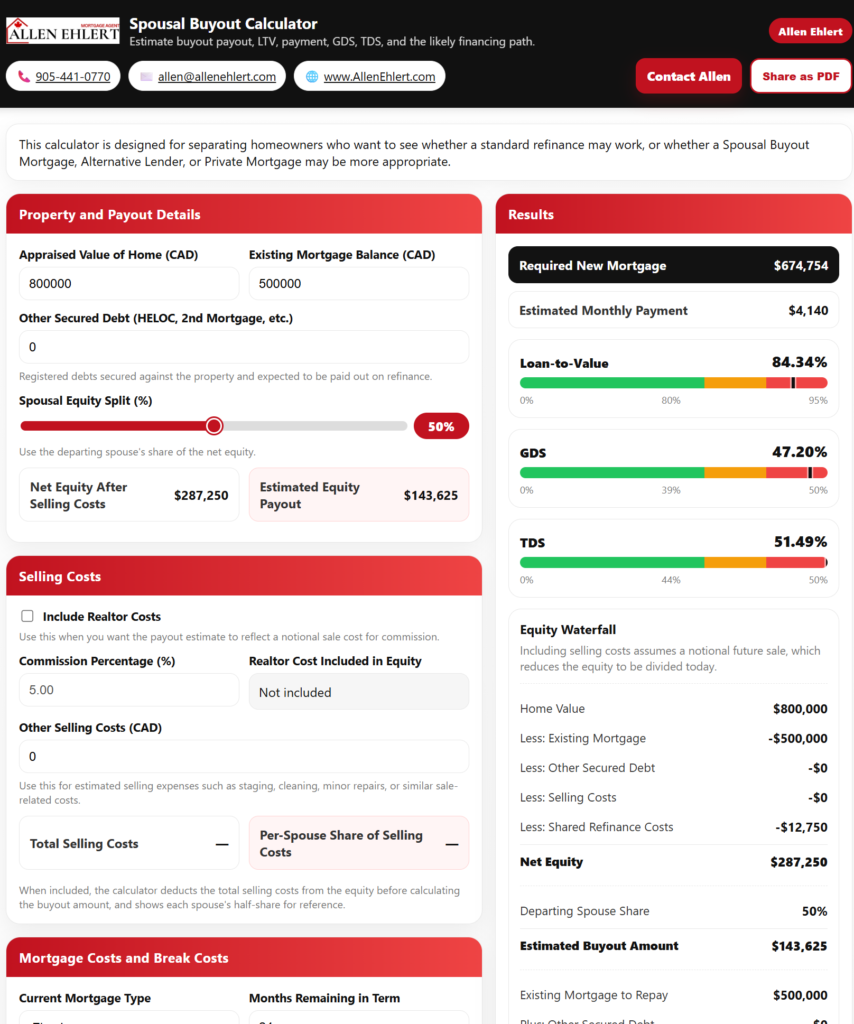
The Spousal Buyout Calculator helps separating homeowners estimate what it would take financially for one spouse to remain in the home while buying out the other spouse’s equity. It goes beyond a simple equity calculation and models the full mortgage scenario—including refinance costs, mortgage penalties, mortgage insurance, affordability ratios, and the likely financing path. Clients turn to a Spousal Buyout when they can’t get a mortgage assumption or they don’t qualify for a Divorce Refinance.
This guide explains how to use each section of the Spousal Buyout Calculator, what the inputs mean, and how to interpret the results so you can understand whether a standard refinance, spousal buyout mortgage, alternative lender, or private financing may be required.
Learn more about Spousal Buyout Mortgages
In this guide:
What This Calculator Is Designed to Do
Information You Will Need Before You Start
Existing Mortgage Break Costs and Fees
Understanding the Results Section
Tips for Using the Calculator Effectively
What This Calculator Is Designed to Do
When one spouse keeps the home after a separation, several financial elements must be considered simultaneously.
The calculator estimates:
- Net equity in the home
- The buyout amount owed to the departing spouse
- Mortgage penalties and refinance costs
- Mortgage default insurance requirements
- The total new mortgage required
- Estimated monthly mortgage payments
- Loan-to-Value ratio (LTV)
- Gross Debt Service ratio (GDS)
- Total Debt Service ratio (TDS)
- The likely financing path
Rather than guessing whether keeping the home might work, this tool models the scenario in the same way lenders evaluate mortgage applications.
Information You Will Need Before You Start
To obtain the most meaningful results, gather the following information:
- Estimated current value of the property
- Outstanding mortgage balance
- Any secured debts such as HELOCs or second mortgages
- The equity division between spouses
- Current mortgage rate and remaining term
- Estimated refinance costs
- Annual income and existing monthly debts
- Property taxes and heating costs
Even approximate figures can provide valuable insight into whether the buyout scenario may work.
Property and Payout Details
This first section establishes the equity position in the home and estimates the payout required to buy out the departing spouse.
Appraised Value of Home
Enter the estimated or appraised value of the property.
If you do not have a formal appraisal, a recent market estimate from a realtor can be used as a starting point.
Existing Mortgage Balance
Enter the current outstanding mortgage balance.
This information can usually be found on your latest mortgage statement.
Other Secured Debt
Include any additional loans registered against the property such as:
- Home Equity Lines of Credit
- Second mortgages
- Private charges
These must typically be paid out as part of the refinance.
Spousal Equity Split
This slider determines what percentage of the equity is owed to the departing spouse.
Common examples include:
- 50% / 50%
- 60% / 40%
- Any negotiated arrangement in a separation agreement
Net Equity
The calculator estimates the equity remaining in the property after debts and optional selling costs are deducted.
Estimated Equity Payout
This amount represents the estimated buyout payment owed to the departing spouse.
Selling Costs
Some separation agreements calculate equity as if the home were sold, which means estimated selling costs are deducted before dividing the equity.
This section allows you to model that scenario.
Include Realtor Costs
When enabled, the calculator deducts an estimated commission from the property value.
Commission Percentage
Enter the estimated real estate commission rate.
A common assumption is approximately 5% of the property value, though this varies.
Other Selling Costs
Additional potential expenses can include:
- Staging
- Cleaning
- Minor repairs
- Legal preparation
Total Selling Costs
The calculator shows the estimated cost of selling the property.
Per-Spouse Share of Selling Costs
This amount represents how much of those costs would typically be attributed to each spouse if the home were sold.
Mortgage Costs and Break Fees
Refinancing often requires breaking the existing mortgage, which may trigger penalties and additional fees.
Current Mortgage Type
Select whether your mortgage is:
Penalty calculations differ depending on the mortgage type.
Months Remaining in Term
Enter the number of months left before your mortgage renews.
This information affects the penalty calculation.
Current Mortgage Rate
Enter the interest rate on your existing mortgage.
Comparable Posted Rate
For fixed mortgages, lenders often use the difference between the current rate and a comparable posted rate when calculating the Interest Rate Differential (IRD) penalty.
NOTE: Calculating exact mortgage penalties are extremely difficult as different lenders use different methods based on different figures. The calculator does it’s best to give you an estimate.
Refinance Costs
Additional refinancing expenses may include:
- Appraisal fees
- Legal fees
- Discharge/Admin Fees
- Administrative discharge fees
- Miscellaneous costs
Split Refinance Costs Between Spouses
When enabled, the calculator deducts refinance costs from the equity before calculating the payout.
This means both spouses share the costs proportionally.
If disabled, the spouse keeping the home absorbs the refinance costs.
Estimated Mortgage Penalty
The calculator estimates the cost of breaking the current mortgage. It can never be definitive.
Mortgage Costs
These are the mortgage financing costs required to remove the old mortgage so a new mortgage can be registered.
Total Costs
This shows the combined estimate of penalties and refinance expenses.
New Refinance Assumptions
This section models what the new mortgage might look like.
New Refinance Interest Rate
Enter the estimated interest rate for the new mortgage.
See my Rates page as a starting point: Rates & Statistics – Allen Ehlert | Mortgage Agent
Amortization Period
Select the amortization period using the slider.
Amortization is limited to 25 years on a Spousal Buyout but can be set lower.
A longer amortization reduces the monthly payment but increases total interest over time.
Default Mortgage Insurance
As the new mortgage exceeds 80% of the property value, mortgage default insurance is required by law.
The calculator automatically evaluates this requirement.
Province
Select the province where the property is located.
Insurance Requirement
This field indicates whether mortgage insurance is required.
Premium Rate
The calculator estimates the premium rate based on the Loan-to-Value ratio.
Required Premium Added to Mortgage
The insurance premium is typically added to the mortgage balance, increasing the loan amount.
Provincial Sales Tax on Premium
Some provinces charge sales tax on mortgage insurance premiums.
In Ontario, Quebec, and Saskatchewan, this tax must be paid in cash at closing and cannot be financed.
Income and Property Costs
Lenders assess whether the remaining spouse can afford the new mortgage using debt service ratios.
Gross Annual Income
Enter your total annual income before taxes.
Other Monthly Debt Payments
Include obligations such as:
- Car loans
- Credit card minimums
- Student loans
- Personal loans
Property Taxes
Enter the annual property tax amount.
Heating Costs
This represents the estimated monthly heating expense.
Many lenders assign a value between $150 to $200 a month for heating costs when calculating housing affordability.
Understanding the Results Section
After entering the information, the calculator generates several key outputs.
Required New Mortgage
This is the estimated mortgage amount required to:
- Pay off the existing mortgage
- Pay out the departing spouse
- Cover the cost of selling (if selected)
- Cover refinance costs (as selected)
- Cover the cost of default mortgage insurance premium
Estimated Monthly Payment
This shows the projected monthly mortgage payment based on the interest rate and amortization selected.
Loan-to-Value (LTV)
Loan-to-Value compares the mortgage size to the property value.
Example:
Home value: $800,000
Mortgage required: $720,000
LTV = 90%
Key benchmarks include:
80% or less — standard refinance range
Up to 95% — potential spousal buyout mortgage range
GDS and TDS Ratios
These ratios measure mortgage affordability.
Gross Debt Service (GDS)
GDS measures housing costs relative to income.
Typical guideline: 39% or lower
Total Debt Service (TDS)
TDS includes housing costs plus other debts.
Typical guideline: 44% or lower
These ratios help determine whether the refinance may qualify with prime lenders.
Equity Waterfall
The Equity Waterfall visually breaks down the calculation step-by-step.
It shows how the numbers flow from:
- Property value
- Existing mortgage
- Other secured debts
- Selling costs
- Shared refinance costs
- Equity division
- Buyout amount
- Final mortgage required
This visualization helps users understand exactly how each variable affects the outcome.
Cash Needed at Closing
Some costs must be paid upfront rather than financed into the mortgage.
This section estimates the cash required at closing, including:
- Legal fees
- Appraisal fees
- Administrative fees
- Provincial tax on mortgage insurance premiums
Mortgage penalties and the insurance premium itself are typically financed into the mortgage.
Recommended Path
Based on the LTV and debt ratios, the calculator suggests a likely financing direction.
Possible outcomes include:
- Standard divorce refinance
- Spousal buyout mortgage
- Alternative lender financing
- Private mortgage solutions
- Sale of the property
This guidance helps users understand where they may fall within the divorce financing ladder.
Example Scenario
Imagine a homeowner named David.
His situation looks like this:
Home value: $800,000
Mortgage balance: $500,000
Equity split: 50%
Income: $140,000
After entering the numbers into the calculator:
Equity in the home is approximately $300,000.
The buyout amount is about $150,000.
The required new mortgage is roughly $650,000.
This results in an LTV slightly above 80%.
In this scenario, the calculator may indicate that a Spousal Buyout Mortgage allowing up to 95% LTV could make the buyout possible.
Without running these numbers, David might have assumed selling the home was his only option.
Tips for Using the Calculator Effectively
For the most useful results:
- Use realistic property value estimates
- Include all secured debts
- Enter accurate income information
- Test multiple interest rate scenarios
- Adjust amortization to explore payment differences
Many users run several scenarios to understand the full range of possibilities.
Contact Me
While the calculator provides valuable insight, it is still an estimate tool.
IMPORTANT: No Calculator can replace professional underwriting!
There are many lenders who take different approaches and use different numbers, we call this lender policies. Moreover, lenders are constantly changing their rates and their policies. Furthermore, lenders frequently grant exceptions to their rules and policies.
This is why, when you are ready, you need to contact me.
Actual mortgage approval depends on additional factors including:
- Credit history
- Employment stability
- Documentation
- Government legislation and guidance
- … and much, much more!
I analyze your full situation and working with you determine the most appropriate, suitable financing strategy for your situation.
Allen’s Final Thoughts
The Spousal Buyout Calculator is designed to help separating homeowners understand whether keeping the home might be financially possible. By modeling equity payouts, refinance costs, mortgage insurance, and affordability ratios, it provides a clear financial picture before you begin the mortgage application process.
For many homeowners navigating separation, seeing the numbers laid out in this way transforms uncertainty into a practical plan for moving forward.